Medicare Part D Enrollment 2026: Avoid 2 Mistakes to Save 20%
Anúncios
Navigating Medicare Part D enrollment 2026 requires diligence to sidestep common errors that can significantly inflate your prescription expenses, with potential savings of up to 20% achievable through informed choices.
Anúncios
As 2026 approaches, understanding your options for Medicare Part D enrollment 2026 becomes more critical than ever. This guide will help you navigate the complexities of prescription drug plans, focusing on two common mistakes that could cost you dearly, and how to avoid them to potentially save up to 20% on your medication costs.
Understanding Medicare Part D: Your Prescription for Savings
Medicare Part D is the federal program that helps Medicare beneficiaries pay for prescription drugs. It’s an essential component of healthcare coverage for millions of Americans, designed to make necessary medications more affordable. However, the landscape of Part D plans can be complex, with various options, formularies, and cost structures.
Anúncios
Choosing the right plan isn’t just about finding the lowest premium. It involves a holistic assessment of your current health needs, anticipated future prescriptions, and how different plans cover those medications. A seemingly cheaper plan might have higher out-of-pocket costs for your specific drugs, leading to unexpected financial burdens.
The purpose of Part D
- Provides coverage for prescription medications.
- Helps reduce out-of-pocket drug costs.
- Offers choices among private insurance plans.
The goal of Part D is to provide financial protection against high prescription drug costs. Without it, many seniors and individuals with disabilities would face prohibitive expenses for their vital medications. Therefore, understanding its structure and how to best utilize it is paramount for financial well-being in retirement.
In essence, Part D is a partnership between the federal government and private insurance companies. These companies offer various plans, each with its own list of covered drugs (formulary), tiered cost-sharing, and network of pharmacies. Your task is to select the plan that best aligns with your individual circumstances.
Mistake 1: Not Reviewing Your Plan Annually for 2026
One of the most significant and costly errors beneficiaries make is failing to re-evaluate their Medicare Part D plan each year. Many assume that if a plan worked well last year, it will continue to be the best option for the upcoming year. This assumption can lead to substantial overspending, especially with changes constantly occurring within plans and your own health.
Insurance companies frequently adjust their formularies, premiums, deductibles, and co-pays. A drug that was covered at a low co-pay last year might move to a higher tier or even be removed from the formulary entirely in 2026. Your own health needs also evolve. New medical conditions might require different medications, or your current prescriptions could change dosage or frequency.
Why annual review is crucial
- Plan formularies change yearly, impacting drug coverage.
- Premiums, deductibles, and co-pays can fluctuate.
- Your health and prescription needs may evolve.
- New plans with better benefits might become available.
Failing to conduct an annual review is akin to driving a car without checking the oil – eventually, you’ll run into problems. For Medicare Part D, these problems manifest as higher out-of-pocket costs for your essential medications. It’s a proactive step that can save you hundreds, if not thousands, of dollars annually.
The annual enrollment period, typically from October 15 to December 7, is your window to make these changes. During this time, you can compare plans, switch plans, or enroll for the first time. Ignoring this period means you’re stuck with your current plan, regardless of how unfavorable it might become for your specific needs.
Mistake 2: Ignoring the Formulary and Tiered Costs
The second major mistake is not thoroughly understanding a plan’s formulary and its tiered cost structure. A plan’s formulary is its list of covered drugs. Not all plans cover all drugs, and even if a drug is covered, its cost to you can vary significantly based on which tier it falls into.
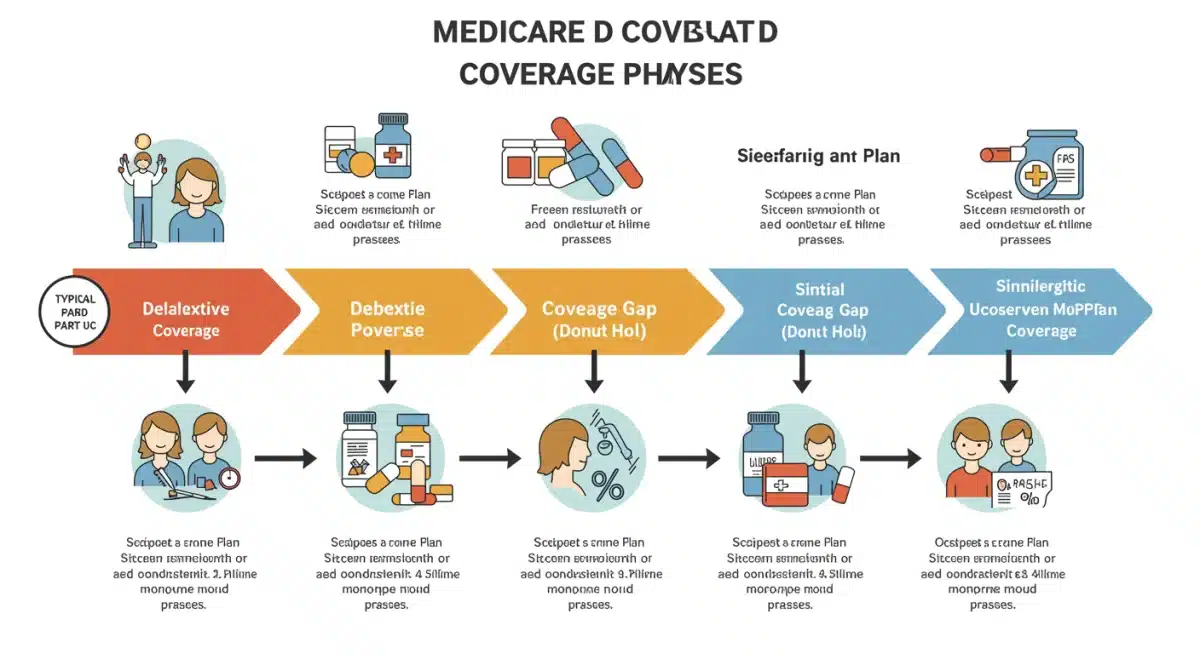
Most Part D plans use a tiered system for prescription drugs. Generally, lower tiers (Tier 1 and 2) include generic and preferred brand-name drugs with lower co-payments. Higher tiers (Tier 3, 4, and 5) consist of non-preferred brand-name drugs, specialty drugs, or biologics, which come with much higher co-payments or co-insurance.

Understanding drug tiers
- Tier 1: Preferred Generics – Lowest cost-sharing.
- Tier 2: Non-Preferred Generics/Preferred Brands – Mid-range cost-sharing.
- Tier 3: Non-Preferred Brands – Higher cost-sharing.
- Tier 4: Specialty Drugs – Highest cost-sharing, often co-insurance.
Before enrolling in any plan, you must check if all your current and anticipated prescriptions are on the plan’s formulary. Furthermore, you need to see which tier each drug falls into. A plan with a low premium might have your essential medications placed in a high tier, leading to significantly higher out-of-pocket costs throughout the year.
It’s also crucial to check for any quantity limits, step therapy requirements, or prior authorization rules for your medications. These restrictions can impact your access to necessary drugs and add to your administrative burden. A little research upfront can prevent major headaches and expenses later.
Strategies to Avoid Costly Medicare Part D Errors for 2026
Avoiding the common mistakes in Medicare Part D enrollment requires a proactive and informed approach. The good news is that with the right strategies, you can optimize your coverage and significantly reduce your prescription drug expenses for 2026. It’s about being diligent and utilizing the resources available to you.
One of the most powerful tools at your disposal is the Medicare Plan Finder tool on Medicare.gov. This free online resource allows you to enter your current medications and dosages, then compare all available Part D plans in your area, showing you estimated annual costs for each plan, including premiums, deductibles, and co-pays. This personalized comparison is invaluable.
Key strategies for smart enrollment
- Utilize the Medicare Plan Finder tool on Medicare.gov.
- Compile a comprehensive list of all your current prescriptions.
- Consider your health outlook for the upcoming year.
- Review potential changes to your preferred pharmacy network.
Don’t just focus on the lowest monthly premium. A plan with a slightly higher premium might offer better coverage for your specific medications, resulting in lower overall annual costs. Look at the estimated annual out-of-pocket costs provided by the Plan Finder, as this gives you a more accurate picture of the true expense.
Additionally, consider calling the plans directly if you have questions about specific drug coverage or restrictions. Sometimes, the online tools might not capture every nuance, and a direct conversation can clarify any uncertainties. Being thorough in your research is your best defense against unexpected costs.
The Impact of the Inflation Reduction Act on Part D in 2026
The Inflation Reduction Act (IRA) of 2022 brings significant changes to Medicare Part D that will continue to roll out and impact beneficiaries in 2026. These changes are designed to lower prescription drug costs and provide greater financial predictability. Understanding these reforms is crucial for making informed enrollment decisions.
One of the most impactful changes for 2026 is the implementation of a $2,000 cap on out-of-pocket prescription drug costs for Part D beneficiaries. This cap will provide immense financial relief for those who previously spent thousands of dollars annually in the catastrophic phase. It effectively eliminates the 5% co-insurance that beneficiaries were responsible for after reaching the catastrophic threshold.
IRA provisions impacting Part D in 2026
- $2,000 annual out-of-pocket cap on prescription costs.
- Elimination of 5% co-insurance in the catastrophic phase.
- Continued negotiation of drug prices for certain high-cost drugs.
- Expansion of eligibility for Low-Income Subsidy (LIS) program.
Another important aspect is the continued negotiation of drug prices by Medicare for certain high-cost medications. While the full impact of these negotiations will unfold over several years, it aims to reduce the overall cost of prescription drugs, potentially leading to lower premiums and out-of-pocket costs for beneficiaries in the long run.
The IRA also expands eligibility for the Low-Income Subsidy (LIS) program, also known as Extra Help. This program assists individuals with limited income and resources in paying for Part D premiums, deductibles, and co-payments. More people qualifying for LIS means greater access to affordable medications for those who need it most, further lowering financial barriers.
Maximizing Your Savings: Beyond Basic Enrollment
To truly maximize your savings on prescription costs, you need to look beyond just the basic enrollment process. While avoiding the two major mistakes is a strong start, there are additional strategies and considerations that can further reduce your out-of-pocket expenses and ensure you get the most value from your Part D plan in 2026.
Consider generic alternatives. Often, a generic version of a brand-name drug is available at a significantly lower cost. Discuss with your doctor if generic alternatives are appropriate for your treatment. Many plans incentivize the use of generics through lower co-pays, making them a smart financial choice.
Additional saving strategies
- Discuss generic alternatives with your healthcare provider.
- Utilize mail-order pharmacies for potential discounts.
- Explore patient assistance programs offered by drug manufacturers.
- Check if your plan offers preferred pharmacy networks with lower costs.
Mail-order pharmacies can also offer cost savings, especially for maintenance medications. Many plans provide a discount or offer a three-month supply for the price of two when using their preferred mail-order service. This can lead to substantial savings over the course of a year, in addition to the convenience.
Furthermore, don’t overlook patient assistance programs. Many pharmaceutical manufacturers offer programs to help eligible patients afford their medications, especially high-cost specialty drugs. These programs can provide significant relief, sometimes even covering the entire cost of a drug. It’s always worth investigating if such options are available for your specific prescriptions.
| Key Point | Brief Description |
|---|---|
| Annual Review | Always review your Part D plan annually to avoid outdated coverage. |
| Formulary Check | Verify all your prescriptions are covered and their tier costs. |
| Utilize Plan Finder | Use Medicare.gov’s tool for personalized cost comparisons. |
| IRA Impact | Be aware of the $2,000 out-of-pocket cap starting in 2026. |
Frequently asked questions about Medicare Part D Enrollment
The annual enrollment period for Medicare Part D typically runs from October 15th to December 7th each year. During this time, beneficiaries can enroll in a new plan, switch plans, or drop their current Part D coverage for the upcoming year.
A formulary is a list of prescription drugs covered by a Medicare Part D plan. It’s crucial because it dictates which medications are covered and at what cost-sharing level. Checking your drugs against a plan’s formulary is essential to ensure your prescriptions are affordable.
The Medicare Plan Finder tool on Medicare.gov allows you to input your medications and compare all available Part D plans in your area. It provides personalized estimates of your total annual out-of-pocket costs, helping you choose the most cost-effective plan for your specific needs.
Starting in 2026, the Inflation Reduction Act caps the annual out-of-pocket prescription drug costs for Medicare Part D beneficiaries at $2,000. This means once you spend $2,000 out-of-pocket in a year, you will pay nothing for covered Part D drugs for the rest of that year.
Generally, yes. Generic drugs are typically much cheaper than their brand-name counterparts because their manufacturers don’t have the initial research and development costs. Most Part D plans place generics in lower cost-sharing tiers, making them a more affordable option for beneficiaries.
Conclusion
Navigating Medicare Part D enrollment 2026 doesn’t have to be a daunting task. By actively avoiding the two most common mistakes—failing to review your plan annually and neglecting to scrutinize formularies and tiered costs—you position yourself to make informed decisions that can lead to significant savings, potentially up to 20% on your prescription drug expenses. The upcoming changes under the Inflation Reduction Act, particularly the $2,000 out-of-pocket cap, further underscore the importance of understanding your benefits. Proactive research, utilizing tools like the Medicare Plan Finder, and exploring additional savings strategies are key to ensuring your healthcare coverage is both comprehensive and financially sound for 2026 and beyond.