2026 Student Loan Repayment: New Federal Programs Explained
Anúncios
Insider’s Guide to 2026 Student Loan Repayment Options: Understanding New Federal Programs
As the landscape of higher education finance continues to evolve, understanding your 2026 student loan repayment options is more crucial than ever. With new federal programs emerging and existing ones undergoing significant reforms, staying informed can save you thousands of dollars and immense financial stress. This comprehensive guide will delve into the intricacies of current and upcoming student loan policies, helping you navigate your repayment journey with confidence.
The year 2026 marks a critical juncture for many borrowers. The dust has settled on the pandemic-era payment pause, and new initiatives are taking center stage, designed to provide more affordable and flexible repayment solutions. Whether you’re a recent graduate, a seasoned borrower, or someone anticipating future student debt, this article will equip you with the knowledge needed to make informed decisions about your 2026 student loan repayment strategy.
Anúncios
The Evolving Landscape of Federal Student Loans
Before diving into specific repayment plans, it’s essential to grasp the broader context of federal student loans. These loans, backed by the U.S. Department of Education, offer distinct advantages over private loans, including fixed interest rates, income-driven repayment options, and pathways to forgiveness. However, their rules and regulations are subject to change, making continuous monitoring vital for effective 2026 student loan repayment.
Key Changes and Their Impact on 2026 Student Loan Repayment
The past few years have brought significant shifts. The COVID-19 payment pause, while offering temporary relief, also highlighted the need for more sustainable long-term solutions. In response, the government has introduced new programs and adjusted existing ones, primarily focusing on affordability and simplifying the repayment process. These changes are particularly relevant as we look towards 2026 student loan repayment.
Anúncios
One of the most impactful developments has been the overhaul of income-driven repayment (IDR) plans, culminating in the introduction of the Saving on a Valuable Education (SAVE) Plan. This plan aims to dramatically reduce monthly payments for many borrowers, offering a more generous approach to calculating discretionary income and shortening the path to forgiveness for certain loan balances. Understanding how the SAVE Plan – and other IDR options – fit into your 2026 student loan repayment strategy is paramount.
Furthermore, efforts to streamline loan forgiveness programs, particularly Public Service Loan Forgiveness (PSLF), have also been underway. While not every borrower will qualify for PSLF, those in eligible public service professions should pay close attention to updated requirements and application processes. These changes could significantly alter the trajectory of your 2026 student loan repayment.
Deep Dive into the SAVE Plan: A Game Changer for 2026 Student Loan Repayment
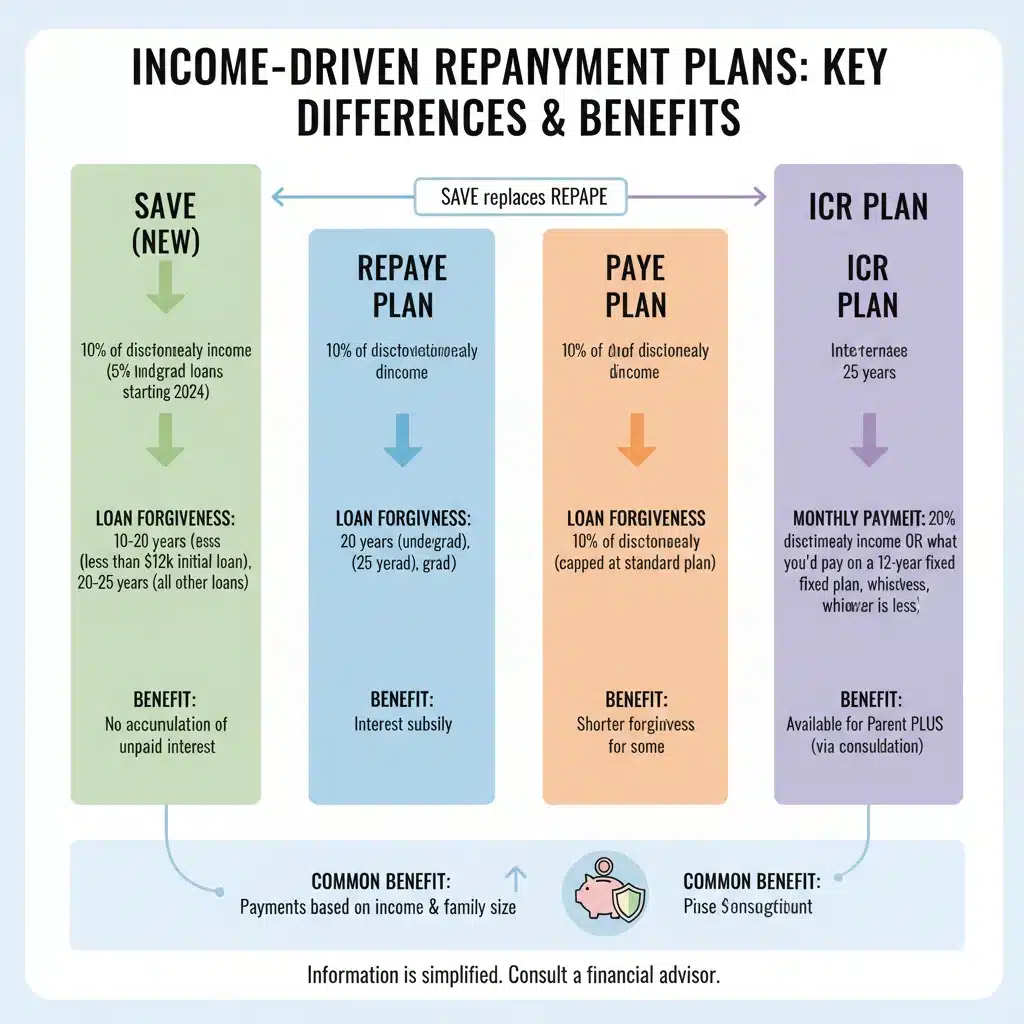
The Saving on a Valuable Education (SAVE) Plan is arguably the most significant development in federal student loan repayment in recent years. It replaces the Revised Pay As You Earn (REPAYE) Plan and offers substantial benefits designed to make monthly payments more affordable and prevent interest capitalization.
How the SAVE Plan Works for 2026 Student Loan Repayment
The core of the SAVE Plan – and all IDR plans – is to calculate your monthly payment based on your income and family size, rather than your loan balance. This ensures that your payments are manageable, even if your income is low. Here’s what makes the SAVE Plan uniquely beneficial for your 2026 student loan repayment:
- Increased Income Exemption: The SAVE Plan protects more of your income from payment calculations. It increases the amount of income considered “non-discretionary” from 150% to 225% of the federal poverty line. This means a larger portion of your income is excluded before your payment is determined, leading to lower – or even $0 – monthly payments for many borrowers.
- Interest Subsidies: A groundbreaking feature of the SAVE Plan is its interest subsidy. If your calculated monthly payment doesn’t cover the full amount of interest that accrues each month, the government covers the remaining interest. This prevents your loan balance from growing due to unpaid interest, a common issue under previous IDR plans. This is a massive advantage for your 2026 student loan repayment strategy, as it means your balance won’t balloon even with low payments.
- Shorter Forgiveness Period for Smaller Balances: For borrowers with original principal balances of $12,000 or less, the SAVE Plan offers loan forgiveness after as few as 10 years of payments. For each additional $1,000 borrowed above $12,000, an additional year of payments is required, up to a maximum of 20 or 25 years (depending on undergraduate or graduate loans). This accelerated forgiveness is a significant benefit for many.
- Exclusion of Spousal Income (for married borrowers filing separately): Unlike some previous IDR plans, if you are married and file your taxes separately, your spouse’s income will not be included in the calculation of your monthly payment under the SAVE Plan. This provides greater flexibility for married borrowers.
These features combine to make the SAVE Plan a powerful tool for managing your 2026 student loan repayment, particularly if you have a lower income relative to your debt or are concerned about interest accumulation.
Other Income-Driven Repayment (IDR) Plans for 2026 Student Loan Repayment
While the SAVE Plan is the newest and often most beneficial IDR option, it’s not the only one. Understanding the other plans – and which one your loans might be eligible for – is crucial for a complete 2026 student loan repayment picture.
Pay As You Earn (PAYE)
The PAYE plan generally caps monthly payments at 10% of your discretionary income, but never more than what you would pay under the Standard Repayment Plan. Forgiveness is granted after 20 years of qualifying payments. Eligibility for PAYE depends on when you took out your loans and your income relative to your debt.
Income-Based Repayment (IBR)
IBR caps your monthly payments at either 10% or 15% of your discretionary income, depending on when you received your first federal student loan. Like PAYE, payments are capped at the Standard Repayment Plan amount. Forgiveness is available after 20 or 25 years of qualifying payments. IBR is often a fallback option if you don’t qualify for other plans.
Income-Contingent Repayment (ICR)
ICR is the oldest IDR plan and typically has the highest payments – either 20% of your discretionary income or what you would pay on a fixed 12-year payment plan, adjusted by income, whichever is less. Forgiveness occurs after 25 years. ICR is the only IDR plan available for Parent PLUS Loans that have been consolidated into a Direct Consolidation Loan.
When considering your 2026 student loan repayment, it’s important to compare these options against the SAVE Plan. For most borrowers, the SAVE Plan will offer the lowest monthly payments and the most favorable terms, but individual circumstances may vary.
Standard and Extended Repayment Plans for 2026 Student Loan Repayment
While IDR plans offer flexibility, they aren’t for everyone. Many borrowers opt for “traditional” repayment plans, which can lead to paying less interest over the life of the loan, albeit with higher monthly payments.
Standard Repayment Plan
This is the default plan for most federal student loans. Payments are fixed and designed to pay off your loan in 10 years (or 30 years for consolidated loans). While monthly payments are typically higher than IDR plans, you’ll pay the least amount of interest overall. This plan is ideal if you can comfortably afford the payments and want to be debt-free quickly.
Graduated Repayment Plan
Under this plan, your payments start low and gradually increase, usually every two years. The loan is still paid off within 10 years (or 30 for consolidated loans). This can be a good option if you expect your income to rise steadily over time, but be aware that you’ll pay more interest than under the Standard Plan.
Extended Repayment Plan
If you have more than $30,000 in federal student loans, you may be eligible for the Extended Repayment Plan. This plan allows you to make either fixed or graduated payments over a period of up to 25 years. While it significantly lowers your monthly payment compared to the Standard Plan, you will pay substantially more interest over the life of the loan. It’s a viable option if you need lower payments but don’t qualify for or prefer not to enroll in an IDR plan for your 2026 student loan repayment.
Loan Forgiveness and Discharge Options for 2026 Student Loan Repayment
Beyond standard repayment, several programs offer the potential for partial or complete loan forgiveness or discharge under specific circumstances. These can be life-changing for eligible borrowers planning their 2026 student loan repayment.
Public Service Loan Forgiveness (PSLF)
PSLF is designed for borrowers who work full-time for a U.S. federal, state, local, or tribal government or a qualifying non-profit organization. After making 120 qualifying monthly payments (usually over 10 years) under a qualifying repayment plan (such as IDR plans), the remaining balance on your Direct Loans may be forgiven. Recent temporary waivers have made it easier for more borrowers to qualify, and it’s crucial to ensure your employer and payments meet the specific criteria for your 2026 student loan repayment strategy.
Teacher Loan Forgiveness
If you teach full-time for five complete and consecutive academic years in a low-income school or educational service agency, you may be eligible for forgiveness of up to $17,500 on your Direct Subsidized and Unsubsidized Loans and your Subsidized and Unsubsidized Federal Stafford Loans. This is a distinct program from PSLF and has different requirements.
Total and Permanent Disability (TPD) Discharge
Borrowers who are totally and permanently disabled may be eligible to have their federal student loans discharged. This typically requires documentation from a physician, the Social Security Administration, or the Department of Veterans Affairs.
Borrower Defense to Repayment
This program allows for loan discharge if your school misled you or engaged in other misconduct in violation of certain state laws. The application process can be complex, but it can provide significant relief if you were defrauded by your educational institution.
Closed School Discharge
If your school closes while you are enrolled or soon after you withdraw, you may be eligible to have your federal student loans discharged. To qualify, you generally cannot have completed your program at another school or transferred your credits.
Consolidation and Refinancing for 2026 Student Loan Repayment
These two options are often confused but serve different purposes in your 2026 student loan repayment plan.
Federal Loan Consolidation
A Direct Consolidation Loan allows you to combine multiple federal student loans into a single loan with one monthly payment. The interest rate is a weighted average of your previous loans, rounded up to the nearest one-eighth of a percent. Consolidation can simplify your payments and may make you eligible for certain IDR plans or PSLF that your individual loans might not have been. It’s particularly useful for older FFEL Program loans to gain access to the full suite of Direct Loan benefits.
Private Student Loan Refinancing
Refinancing involves taking out a new loan from a private lender to pay off your existing student loans (federal, private, or both). The goal is typically to secure a lower interest rate or a more favorable repayment term. While it can save you money, be cautious: refinancing federal loans into a private loan means losing access to federal benefits like IDR plans, forgiveness programs, and deferment/forbearance options. This decision should be carefully weighed against your 2026 student loan repayment goals.
Strategies for Optimizing Your 2026 Student Loan Repayment
With so many options, developing a personalized strategy is key. Here are steps to optimize your 2026 student loan repayment:
1. Know Your Loans
Before you can make any decisions, you need to know exactly what you owe. Access your loan information through StudentAid.gov. This federal portal provides details on your federal loan types, servicers, interest rates, and balances. For private loans, contact your lender directly.
2. Assess Your Financial Situation
Create a detailed budget. Understand your monthly income, essential expenses, and discretionary spending. This will help you determine how much you can realistically afford to pay towards your loans without compromising other financial goals. Your current and projected income is critical for choosing the right 2026 student loan repayment plan.
3. Compare Repayment Plans
Use the Loan Simulator tool on StudentAid.gov. This powerful resource allows you to compare different federal repayment plans – including IDR options – side-by-side. It estimates your monthly payments, total amount paid, and potential forgiveness amounts under each plan. This is invaluable for planning your 2026 student loan repayment.
4. Consider the SAVE Plan First
For many borrowers, the SAVE Plan will offer the most favorable terms, especially concerning lower monthly payments and interest subsidies. Even if you were on a different IDR plan, you might benefit from switching to SAVE. This should be one of your first considerations for 2026 student loan repayment.
5. Explore Forgiveness Options
If you work in public service or a qualifying teaching role, actively pursue PSLF or Teacher Loan Forgiveness. Ensure you understand all the requirements and submit the necessary paperwork (like the PSLF Employer Certification Form) regularly.
6. Don’t Be Afraid to Consolidate – Carefully
If you have older FFEL Program loans or want to simplify your payments, federal loan consolidation can be beneficial. Just ensure it aligns with your long-term goals, especially if you’re pursuing PSLF.
7. Avoid Default
If you’re struggling to make payments, contact your loan servicer immediately. They can discuss options like deferment, forbearance, or switching to an IDR plan. Missing payments can severely damage your credit and lead to serious consequences.
8. Stay Informed
Student loan policies can change. Regularly check official sources like StudentAid.gov and your loan servicer’s website for the latest updates and announcements. Being proactive will keep your 2026 student loan repayment strategy on track.
Important Considerations for All Borrowers
Beyond selecting a repayment plan, several other factors can influence your 2026 student loan repayment experience.
Annual Recertification for IDR Plans
If you’re on an IDR plan, you’ll need to recertify your income and family size annually. Failing to do so can result in your payments increasing and unpaid interest capitalizing. Set reminders and submit your documentation on time.
Tax Implications of Forgiveness
While federal student loan forgiveness is currently tax-free at the federal level until 2025, this provision may not extend to 2026 student loan repayment. Some states may also tax forgiven amounts. It’s crucial to consult with a tax professional as you approach forgiveness, especially if it occurs in 2026 or beyond.
Emergency Savings
Always prioritize building an emergency fund. Having 3-6 months of living expenses saved can provide a crucial buffer if you face unexpected financial hardship, preventing you from missing loan payments.
Credit Score Impact
Your student loan repayment history directly impacts your credit score. Making on-time payments consistently will build a positive credit history, while missed payments can cause significant damage. A good credit score is vital for future financial endeavors, from buying a home to securing other loans.
Conclusion: Taking Control of Your 2026 Student Loan Repayment
The journey of student loan repayment can feel overwhelming, but with the right information and a proactive approach, you can navigate it successfully. The new federal programs, particularly the SAVE Plan, offer unprecedented opportunities for borrowers to manage their debt more affordably. By understanding your options, leveraging available tools, and staying informed, you can take control of your 2026 student loan repayment and work towards a brighter financial future.
Don’t wait until the last minute to review your situation. Start exploring your options today, utilize the resources provided by the Department of Education, and don’t hesitate to contact your loan servicer if you have questions. Your financial well-being depends on it.