ACA Subsidies 2026: Up to 80% Healthcare Coverage Explained
Anúncios
Healthcare Subsidies in 2026: How the Affordable Care Act is Providing Up to 80% Coverage for Many Americans
The landscape of healthcare in the United States is constantly evolving, and for millions of Americans, the Affordable Care Act (ACA) continues to be a lifeline. As we look ahead to 2026, the provisions within the ACA, particularly its robust subsidy programs, are set to provide unprecedented levels of financial assistance, potentially covering up to 80% of healthcare costs for eligible individuals and families. This comprehensive guide will delve into the intricacies of these ACA subsidies 2026, explaining who qualifies, how they work, and what you need to know to take advantage of these vital benefits.
Anúncios
For many, the cost of health insurance has been a significant barrier to accessing necessary medical care. The ACA was designed to address this very issue, and its ongoing enhancements ensure that more people can afford comprehensive coverage. Understanding the details of ACA subsidies 2026 is crucial for anyone seeking to navigate the complex world of health insurance.
Understanding the Affordable Care Act (ACA) and its Core Principles
Before we dive into the specifics of the ACA subsidies 2026, it’s essential to grasp the foundational principles of the Affordable Care Act itself. Enacted in 2010, the ACA, often referred to as Obamacare, aimed to expand health insurance coverage, control healthcare costs, and improve healthcare quality. Key components include:
Anúncios
- Individual Mandate (initially): Required most Americans to have health insurance or pay a penalty (though the penalty was later repealed at the federal level).
- Health Insurance Marketplaces: Online platforms where individuals and small businesses can compare and purchase health insurance plans.
- Guaranteed Issue: Insurers cannot deny coverage or charge more based on pre-existing conditions.
- Essential Health Benefits: All plans offered on the Marketplace must cover ten categories of services, including emergency services, maternity care, prescription drugs, and mental health services.
- Medicaid Expansion: Allowed states to expand Medicaid eligibility to cover more low-income adults.
- Subsidies: Financial assistance to help make insurance premiums and out-of-pocket costs more affordable.
These principles work in tandem to create a more accessible and equitable healthcare system. The subsidies, in particular, are the cornerstone of affordability, directly impacting how much individuals pay for their monthly premiums and, in some cases, their deductibles, copayments, and co-insurance.
The Evolution of ACA Subsidies: What’s New for 2026?
The ACA’s subsidy structure has seen significant adjustments over the years, primarily aimed at increasing affordability and expanding eligibility. The most impactful changes came with the American Rescue Plan Act (ARPA) in 2021 and were extended by the Inflation Reduction Act (IRA) in 2022. These legislative acts significantly enhanced the ACA subsidies, making them more generous and accessible to a broader range of income levels. While some provisions of these acts are set to expire, the core enhancements to the ACA subsidies 2026 are expected to remain robust, continuing to offer substantial relief.
Historically, premium tax credits were limited to individuals earning between 100% and 400% of the Federal Poverty Level (FPL). Under the enhanced subsidies, this income cap has been removed, meaning individuals earning above 400% FPL can also qualify for assistance if their healthcare premiums exceed a certain percentage of their household income. This is a game-changer for middle-income families who previously found themselves ineligible for help, facing high premiums that made insurance unaffordable.
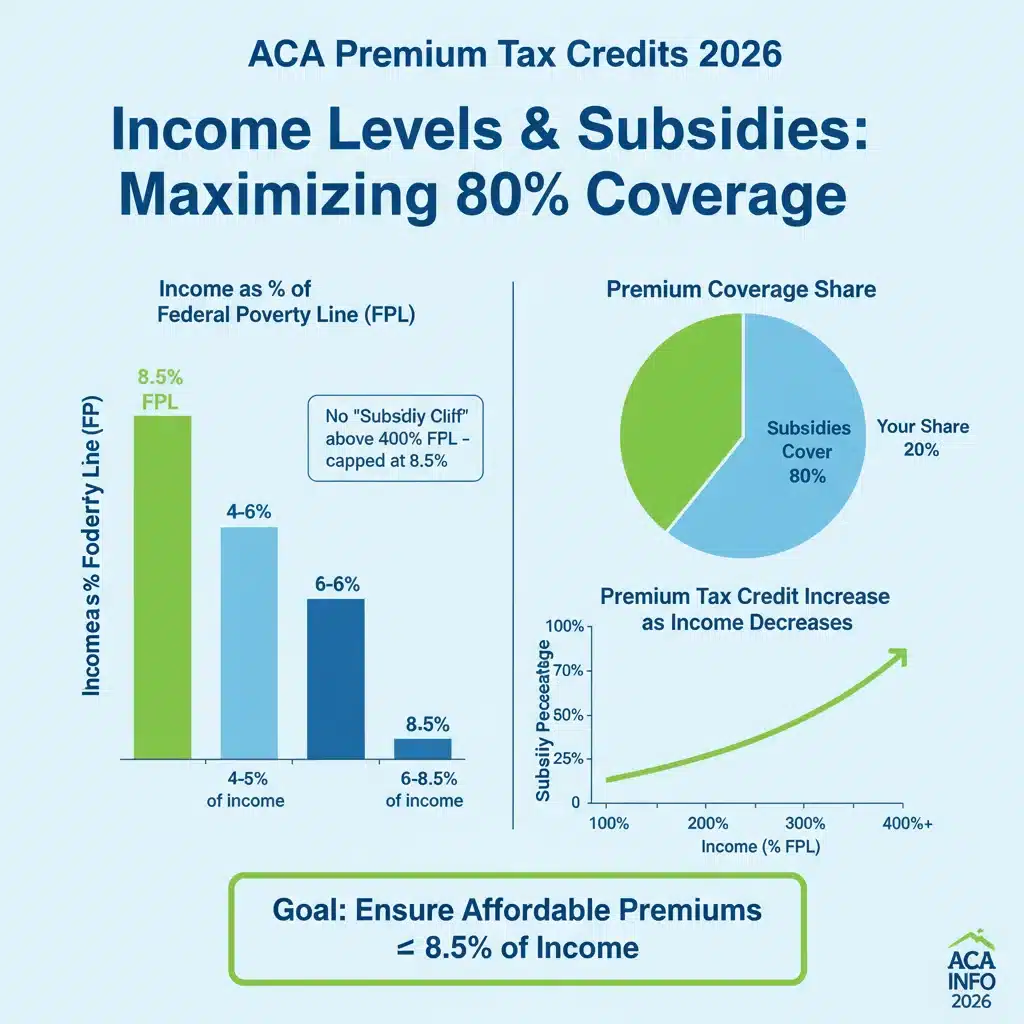
For 2026, the focus remains on ensuring that no one has to pay more than 8.5% of their household income for a benchmark silver plan premium. This cap is a critical protection, especially for those with higher incomes who might otherwise face exorbitant costs. The ACA subsidies 2026 are designed to bridge the gap between what a household can afford and the actual cost of health insurance.
Who Qualifies for ACA Subsidies in 2026? Eligibility Criteria
Eligibility for ACA subsidies 2026 primarily hinges on your household income and household size, relative to the Federal Poverty Level (FPL). Here’s a breakdown of the key criteria:
Income Requirements
The most significant factor is your Modified Adjusted Gross Income (MAGI) in relation to the FPL. For 2026, the FPL thresholds will be updated, so it’s important to refer to the most current figures when they become available. Generally:
- Below 100% FPL: In states that have expanded Medicaid, individuals below 138% FPL are typically eligible for Medicaid. In non-expansion states, individuals below 100% FPL may fall into the ‘coverage gap’ and not qualify for subsidies or Medicaid.
- Between 100% and 400% FPL: Most individuals and families in this income range will qualify for significant premium tax credits, reducing their monthly premiums. The lower your income within this range, the larger your subsidy.
- Above 400% FPL: Under the enhanced ACA subsidies 2026, even those earning above 400% FPL can qualify if the cost of a benchmark silver plan would exceed 8.5% of their household income. This effectively eliminates the ‘subsidy cliff’ that previously prevented many middle-income families from receiving assistance.
It’s crucial to remember that the FPL changes annually, so checking the most up-to-date figures from HealthCare.gov or your state’s marketplace is essential when enrolling for 2026 coverage.
Other Eligibility Factors
- Not Offered Affordable Employer Coverage: You generally won’t qualify for ACA subsidies 2026 if you have access to affordable health insurance through your employer or your spouse’s employer. Employer-sponsored coverage is considered affordable if the employee’s share of the premium for self-only coverage is less than 9.5% (adjusted annually) of their household income.
- Lawful Presence in the U.S.: You must be a U.S. citizen or lawfully present immigrant to qualify.
- Not Incarcerated: Individuals who are incarcerated are generally not eligible for Marketplace plans or subsidies.
The marketplace will automatically determine your eligibility for premium tax credits and, if applicable, cost-sharing reductions, based on the information you provide in your application.
Types of ACA Subsidies 2026: Premium Tax Credits and Cost-Sharing Reductions
There are two main types of ACA subsidies 2026 designed to make healthcare more affordable:
1. Premium Tax Credits (PTC)
These are the most common type of subsidy and are designed to lower your monthly health insurance premiums. When you apply through the Marketplace, you can choose to have these credits paid directly to your insurance company each month, reducing your out-of-pocket premium costs immediately. Alternatively, you can pay the full premium and claim the entire tax credit when you file your federal income taxes.
The amount of your premium tax credit depends on your income, household size, and the cost of the benchmark silver plan in your area. The benchmark plan is the second-lowest-cost silver plan available in your region. The ACA subsidies 2026 ensure that your premium contribution for this benchmark plan does not exceed a certain percentage of your income (currently capped at 8.5%). If you choose a plan that costs more than the benchmark plan, you’ll pay the difference. If you choose a less expensive plan, you’ll pay less.
2. Cost-Sharing Reductions (CSR)
Cost-sharing reductions go beyond lowering your monthly premiums; they reduce the amount you have to pay for deductibles, copayments, and co-insurance when you use medical services. CSRs are available to individuals and families with incomes up to 250% of the FPL. To receive CSRs, you must enroll in a Silver plan.
When you qualify for CSRs, your Silver plan will have lower deductibles, copayments, and out-of-pocket maximums than a standard Silver plan. This means you pay less when you actually receive care, offering significant financial protection, especially for those with chronic conditions or unexpected medical emergencies. It’s important to note that you cannot receive CSRs with Bronze, Gold, or Platinum plans, even if you qualify based on income.
How ACA Subsidies Can Provide Up to 80% Coverage
The claim that ACA subsidies 2026 can provide up to 80% coverage for many Americans is not an exaggeration. This high level of coverage is achieved through the combined power of premium tax credits and cost-sharing reductions.
The Power of Premium Tax Credits
For individuals and families with lower incomes, premium tax credits can be substantial. For example, a household at 150% of the FPL might only be expected to contribute a very small percentage of their income towards premiums. The rest of the premium for a benchmark plan would be covered by the premium tax credit. In many cases, this can result in premiums that are extremely low, or even $0 per month, for a basic plan.
The Impact of Cost-Sharing Reductions on Total Costs
When you combine significant premium tax credits with cost-sharing reductions (CSRs), the total out-of-pocket burden for healthcare can be dramatically reduced. CSRs effectively boost the actuarial value of a Silver plan. A standard Silver plan covers about 70% of average healthcare costs, with the enrollee paying the remaining 30% through deductibles, copays, and co-insurance. However, with CSRs, the actuarial value of a Silver plan can increase to 73%, 87%, or even 94%, depending on your income level.
For example, an individual with an income at 150% FPL who enrolls in a Silver plan with CSRs would essentially be getting a plan that covers 94% of their average healthcare costs. This means their out-of-pocket expenses for deductibles, copays, and co-insurance are significantly lower, making their overall healthcare costs much more manageable. When you factor in a low or $0 premium due to premium tax credits, the combination can indeed lead to a scenario where the government assistance covers a very large portion – up to 80% or even more – of an individual’s total healthcare expenditures.
It’s important to understand that the 80% coverage figure refers to the total cost burden, including both premiums and out-of-pocket expenses, for eligible individuals utilizing both types of ACA subsidies 2026. This level of support makes quality healthcare genuinely affordable for millions.
Navigating the Health Insurance Marketplace for 2026 Enrollment
Enrolling in a health insurance plan with ACA subsidies 2026 requires navigating the Health Insurance Marketplace. Here’s a step-by-step guide:
1. Gather Your Information
Before you begin, have the following information ready for all members of your household:
- Social Security numbers (or document numbers for lawfully present immigrants).
- Employer and income information for every member of your household (e.g., pay stubs, W-2s, tax returns).
- Information about any job-based health insurance available to you or your family.
2. Create an Account on HealthCare.gov or Your State Marketplace
Most states use the federal HealthCare.gov platform, but some states operate their own marketplaces. You’ll need to create an account with a username and password.
3. Complete the Application
The application will ask for details about your household size, income, and any current health insurance. This information is crucial for determining your eligibility for ACA subsidies 2026.
4. Review Your Eligibility Results
After submitting your application, the Marketplace will immediately inform you if you qualify for premium tax credits, cost-sharing reductions, or Medicaid/CHIP. It will show you the estimated amount of your premium tax credit.
5. Compare Plans and Choose the Best Option
Once you know your subsidy amount, you can compare available plans. Pay attention to:
- Metal Tiers: Bronze (low premium, high out-of-pocket), Silver (moderate premium, moderate out-of-pocket, required for CSRs), Gold (high premium, low out-of-pocket), Platinum (highest premium, lowest out-of-pocket).
- Network Type: HMO, PPO, EPO, POS – affects which doctors and hospitals you can use.
- Deductibles, Copayments, Co-insurance, and Out-of-Pocket Maximums: Understand how much you’ll pay for care.
- Prescription Drug Coverage: Check if your medications are covered.
- Doctor and Hospital Preferences: Ensure your preferred providers are in-network.
Remember, if you qualify for cost-sharing reductions, you MUST choose a Silver plan to receive those benefits. Even if a Bronze plan seems cheaper upfront, a Silver plan with CSRs might save you more money in the long run if you anticipate using medical services.
6. Enroll in Your Chosen Plan
Once you’ve made your decision, you can enroll directly through the Marketplace. You’ll typically make your first premium payment to your insurance company directly.
Important Considerations for ACA Subsidies 2026
Reporting Income Changes
It is critically important to report any changes in your household income or size to the Marketplace as soon as possible. If your income increases and you don’t report it, you might receive too much in premium tax credits, which you would then have to pay back at tax time. Conversely, if your income decreases, you might be eligible for more assistance, and reporting the change could lower your monthly premiums or increase your cost-sharing reductions.
Open Enrollment Period
The primary time to enroll in a new plan or change your existing plan is during the annual Open Enrollment Period, which typically runs from November 1st to January 15th for coverage starting the following year. For ACA subsidies 2026, mark these dates on your calendar.
Special Enrollment Periods
Outside of Open Enrollment, you may qualify for a Special Enrollment Period (SEP) if you experience certain life events, such as:
- Getting married or divorced.
- Having a baby or adopting a child.
- Losing other health coverage (e.g., job loss, aging off a parent’s plan).
- Moving to a new area.
- Changes in income that affect eligibility for subsidies.
If you experience a qualifying life event, you typically have 60 days from the event to enroll in a new plan.
Understanding Your Tax Responsibilities
Premium tax credits are reconciled when you file your federal income taxes. You’ll receive Form 1095-A from the Marketplace, which reports the amount of premium tax credits paid on your behalf. You’ll use this form to complete Form 8962, Premium Tax Credit (PTC), to reconcile the amount of tax credit you received with the amount you were eligible for based on your actual income for the year. This is why accurate income reporting throughout the year is so vital.
The Broader Impact of ACA Subsidies 2026
The continued strength and reach of ACA subsidies 2026 have far-reaching implications beyond individual financial relief. They contribute to:
- Increased Health Security: More people with insurance means fewer medical bankruptcies and greater peace of mind.
- Improved Public Health: With greater access to preventive care and early treatment, communities become healthier.
- Economic Stability: A healthier workforce is a more productive workforce, and reduced medical debt can free up household income for other expenditures.
- Reduced Uncompensated Care: Hospitals and healthcare providers face less financial strain from treating uninsured patients.
These subsidies are not just about helping individuals; they are about strengthening the entire healthcare system and economy. The ability for many Americans to secure up to 80% coverage through ACA subsidies 2026 represents a significant achievement in making healthcare a right, not a privilege.
Future Outlook and Potential Changes
While the ACA subsidies 2026 are expected to remain robust, the political landscape surrounding healthcare is always subject to change. It’s important for consumers to stay informed about any potential legislative developments that could impact the ACA or its subsidy programs.
Advocates continue to push for making the enhanced subsidies permanent, arguing that they are crucial for maintaining affordability and expanding coverage. The ongoing debate highlights the importance of the ACA in the national conversation about healthcare access and costs.
Regardless of future legislative actions, the current framework for ACA subsidies 2026 offers a powerful tool for millions to access affordable, quality health insurance. Staying proactive in understanding your eligibility and enrolling during the appropriate periods will ensure you maximize your benefits.
Conclusion: Securing Your Healthcare Future with ACA Subsidies 2026
The Affordable Care Act continues to be a cornerstone of healthcare accessibility in the United States. For 2026, its enhanced subsidy programs are set to offer significant financial relief, potentially covering up to 80% of healthcare costs for eligible individuals and families. By understanding the eligibility criteria, the types of subsidies available (premium tax credits and cost-sharing reductions), and how to navigate the Health Insurance Marketplace, you can secure affordable, comprehensive health coverage.
Don’t let the complexities of health insurance deter you. The ACA subsidies 2026 are designed to make quality care within reach. Take the time to gather your information, explore your options on HealthCare.gov or your state’s marketplace, and enroll during the Open Enrollment Period. Your health and financial well-being depend on it. By leveraging these powerful subsidies, you can ensure that you and your loved ones have the protection you need for a healthier, more secure future.