Navigating 2026 Student Loan Debt: New Repayment & Forgiveness Options
Anúncios
Navigating The 2026 Student Loan Debt Landscape: New Repayment Options and Forgiveness Programs to Consider
Anúncios
The year 2026 is rapidly approaching, bringing with it a renewed focus on the ever-evolving challenge of student loan debt. For millions of Americans, student loans represent a significant financial burden, impacting life decisions from career choices to homeownership. As policies shift and economic conditions fluctuate, understanding the current landscape of student loan debt 2026 is crucial for effective management and planning. This comprehensive guide aims to demystify the complexities of federal and private student loans, highlight new repayment options, and shed light on various forgiveness programs that could offer significant relief.
Student loan debt has become a pervasive issue, with cumulative balances reaching staggering figures. The impact extends beyond individual borrowers, influencing the broader economy. Recognizing this, policymakers and financial institutions continually introduce new measures to address the crisis. For those grappling with student loan debt 2026, staying informed about these changes is not just beneficial, but essential. From income-driven repayment (IDR) plans to specialized forgiveness programs, a multitude of avenues exist for borrowers to explore. However, the sheer volume of information can be overwhelming, making it difficult to discern the most suitable path.
This article will delve deep into the intricacies of managing your student loans in 2026. We will explore the latest updates to federal repayment plans, including the highly discussed SAVE plan, and revisit established programs like Public Service Loan Forgiveness (PSLF). Furthermore, we will touch upon strategies for private student loans, which, while not eligible for federal programs, still require careful consideration. Our goal is to equip you with the knowledge and tools necessary to navigate your student loan debt 2026 with confidence, making informed decisions that lead to financial stability and peace of mind.
Anúncios
Understanding the Current State of Student Loan Debt in 2026
As we look towards 2026, the student loan debt landscape continues to be a dynamic and often challenging environment. The cumulative national student loan debt remains a significant economic factor, impacting millions of households. Various factors contribute to this persistent challenge, including rising tuition costs, stagnant wage growth for recent graduates, and the compounding effect of interest. While the exact figures fluctuate, the underlying issues persist, making proactive management of student loan debt 2026 more important than ever.
The federal government plays a pivotal role in shaping the student loan environment through legislation and policy changes. Recent years have seen significant reforms, and more are anticipated as we approach 2026. These changes often aim to provide greater flexibility and relief to borrowers, but they also introduce new layers of complexity. Understanding the distinction between federal and private loans is fundamental, as each category operates under different rules and offers distinct sets of repayment and forgiveness options. Federal loans, backed by the U.S. Department of Education, typically come with more borrower protections and income-driven repayment plans. Private loans, issued by banks and other financial institutions, generally offer fewer flexible options and lack federal forgiveness programs.
Economic indicators also play a crucial role in the student loan debt 2026 outlook. Inflation rates, interest rate trends, and the overall job market significantly influence borrowers’ ability to repay their loans. A robust economy might offer more job opportunities and higher salaries, making repayment more manageable. Conversely, economic downturns can exacerbate financial struggles, highlighting the need for robust safety nets like IDR plans. Staying abreast of these broader economic trends can help borrowers anticipate potential challenges and adjust their financial strategies accordingly. The interplay of these factors creates a complex web that borrowers must navigate to successfully manage their student loan debt 2026.
Key Federal Student Loan Repayment Options for 2026
For individuals managing federal student loan debt 2026, a variety of repayment plans are available, each designed to cater to different financial situations. These plans are broadly categorized into standard, graduated, extended, and income-driven repayment (IDR) plans. Choosing the right plan is paramount to effectively managing your debt and avoiding default.
Standard Repayment Plan
The Standard Repayment Plan is the default option for most federal student loans. Under this plan, borrowers make fixed monthly payments for up to 10 years (or up to 30 years for consolidated loans). While it typically results in the lowest total interest paid over the life of the loan, the monthly payments can be substantial, making it challenging for those with lower incomes or high debt balances. For many with student loan debt 2026, this plan might not be the most sustainable option.
Graduated Repayment Plan
The Graduated Repayment Plan offers lower initial payments that gradually increase every two years, typically over a 10-year period. This plan is designed for borrowers who expect their income to grow over time. While it provides some initial relief, the total interest paid will be higher than under the Standard Plan, and payments can become quite high in later years. It’s a viable option for those confident in their future earning potential but requires careful budgeting as payments rise.
Extended Repayment Plan
For borrowers with more than $30,000 in outstanding federal student loan debt, the Extended Repayment Plan allows for payments to be stretched out over a period of up to 25 years. Payments can be fixed or graduated. This plan significantly lowers monthly payments compared to the Standard or Graduated plans, but it also means paying substantially more interest over the long term. It’s an option for those seeking to reduce their monthly burden on their student loan debt 2026, but at a higher overall cost.
Income-Driven Repayment (IDR) Plans: A Lifeline for Many
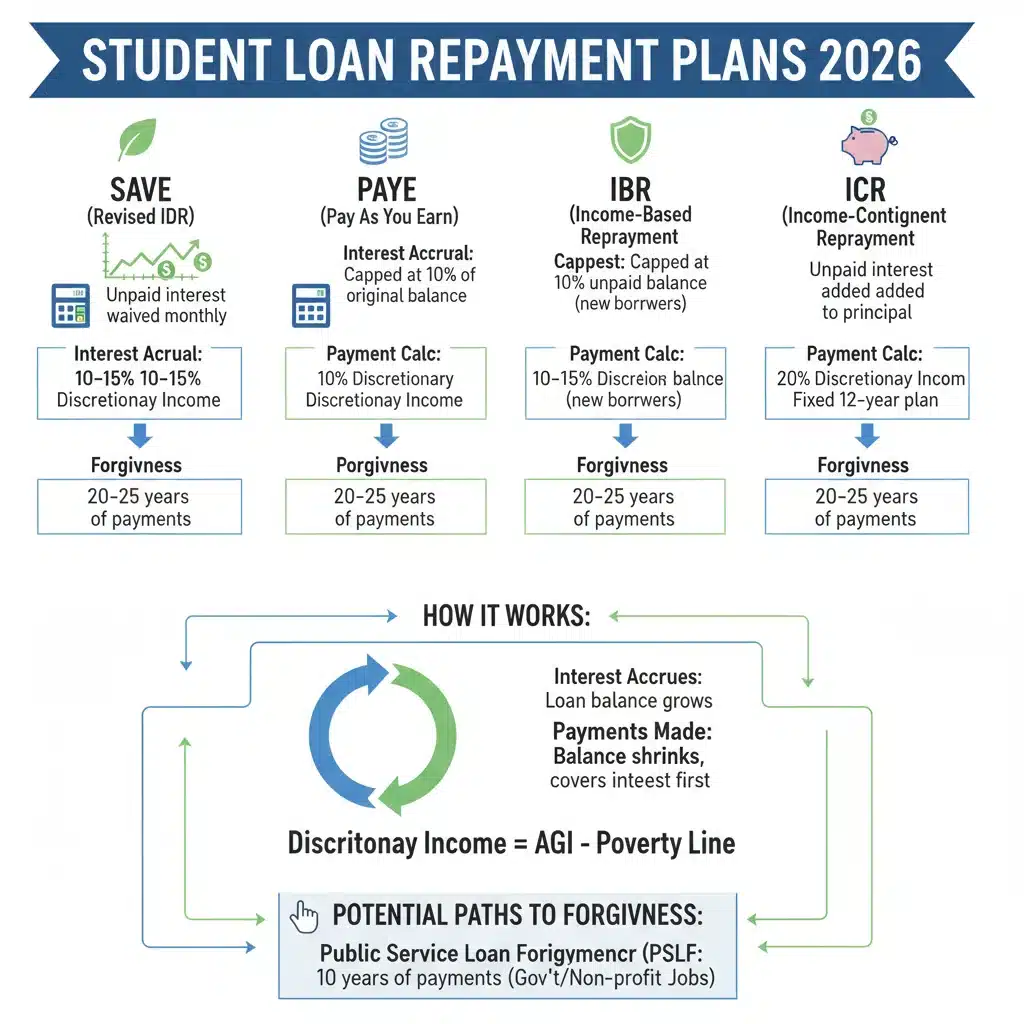
Income-Driven Repayment (IDR) plans are arguably the most impactful options for borrowers struggling with student loan debt 2026. These plans adjust monthly payments based on your income and family size, typically capping them at an affordable percentage of your discretionary income. Any remaining loan balance after a certain number of years (usually 20 or 25, depending on the plan and loan type) is forgiven. The interest on IDR plans can sometimes be subsidized, preventing your balance from growing even if your payments are low. The main IDR plans include:
- Pay As You Earn (PAYE): Payments are generally 10% of discretionary income, for 20 years.
- Income-Based Repayment (IBR): Payments are generally 10% or 15% of discretionary income, for 20 or 25 years.
- Income-Contingent Repayment (ICR): Payments are the lesser of 20% of discretionary income or what you’d pay on a fixed 12-year plan, for 25 years.
- Revised Pay As You Earn (REPAYE), now known as SAVE: This is a critical plan for student loan debt 2026.
The SAVE Plan: A Game Changer for Student Loan Debt 2026
The Saving on a Valuable Education (SAVE) Plan, which replaced the REPAYE Plan, is a significant development in the student loan debt 2026 landscape. It offers the most generous terms for many borrowers, particularly those with lower incomes or high loan balances. Key features of the SAVE Plan include:
- Lower Monthly Payments: For undergraduate loans, payments are calculated at 5% of discretionary income, down from 10% under REPAYE. For graduate loans, it remains 10%, and for a mix of both, it’s a weighted average.
- Higher Discretionary Income Threshold: The amount of income considered ‘discretionary’ is increased from 150% to 225% of the federal poverty line, meaning more of your income is protected and not factored into your payment calculation. This significantly reduces monthly payments for many.
- Interest Subsidy: Perhaps the most impactful feature, the SAVE Plan prevents your loan balance from growing due to unpaid interest. If your monthly payment doesn’t cover the accrued interest, the government covers the difference, ensuring your principal balance doesn’t increase. This is a crucial benefit for those with student loan debt 2026 struggling to make ends meet.
- Shorter Forgiveness Timeline for Small Balances: Borrowers with original loan balances of $12,000 or less can receive forgiveness after as few as 10 years of payments, with an additional year added for every $1,000 borrowed above $12,000, up to a maximum of 20 or 25 years.
The SAVE Plan is designed to be particularly beneficial for low-income borrowers and those with substantial student loan debt 2026, potentially offering significantly lower payments and preventing the frustrating experience of seeing their loan balance grow despite making consistent payments. It’s highly recommended for anyone eligible to explore this option thoroughly.
Student Loan Forgiveness and Discharge Programs for 2026
Beyond standard and income-driven repayment, several federal programs offer avenues for student loan forgiveness or discharge, providing substantial relief for eligible borrowers navigating student loan debt 2026. These programs are often tied to specific professions, circumstances, or long-term repayment.
Public Service Loan Forgiveness (PSLF)
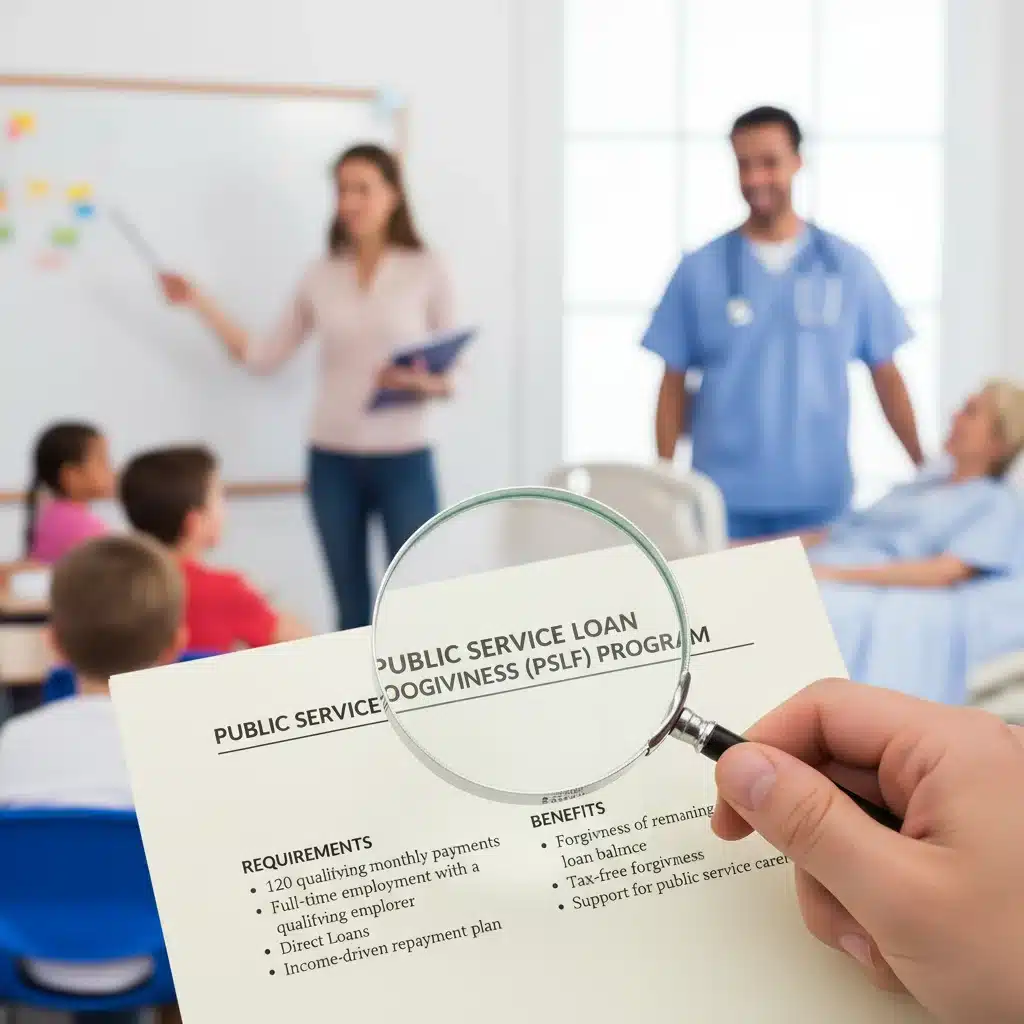
The Public Service Loan Forgiveness (PSLF) program is designed to forgive the remaining balance on Direct Loans for borrowers who work full-time for a qualifying employer and make 120 qualifying monthly payments under a qualifying repayment plan. Qualifying employers include government organizations (federal, state, local, or tribal), non-profit organizations (501(c)(3)), and other non-profits that provide certain public services. This program can be a game-changer for those in public service careers with significant student loan debt 2026.
Key aspects of PSLF for 2026:
- Qualifying Employment: Must be full-time (at least 30 hours per week) for a government or eligible non-profit organization.
- Qualifying Loans: Only Direct Loans are eligible. Other federal loans (like FFEL or Perkins) must be consolidated into a Direct Consolidation Loan to qualify.
- Qualifying Payments: Payments must be made on time, for the full amount due, after October 1, 2007, under a qualifying repayment plan (typically an IDR plan).
- Temporary Expanded PSLF (TEPSLF): While the original PSLF requirements are strict, TEPSLF was introduced to offer a second chance to borrowers who were denied PSLF because they were in the wrong repayment plan. Borrowers must apply for PSLF first to be considered for TEPSLF. It’s crucial to regularly submit the PSLF Employment Certification Form to track progress.
For those committed to public service, understanding and leveraging PSLF is a critical component of managing student loan debt 2026.
Teacher Loan Forgiveness (TLF)
The Teacher Loan Forgiveness (TLF) program offers up to $17,500 in forgiveness for Direct Subsidized/Unsubsidized Loans and Federal Stafford Loans. To qualify, teachers must teach full-time for five complete and consecutive academic years in a low-income elementary or secondary school or educational service agency. The amount of forgiveness depends on the subject taught. Highly qualified math, science, or special education teachers can receive the full $17,500, while other qualifying teachers may receive up to $5,000. This program can significantly reduce student loan debt 2026 for eligible educators.
Disability Discharge
Borrowers who are totally and permanently disabled (TPD) may be eligible for a Total and Permanent Disability Discharge. This discharge eliminates the obligation to repay federal student loans (Direct Loans, FFEL Program loans, and Perkins Loans) and/or to complete a TEACH Grant service obligation. Eligibility can be demonstrated through a Department of Veterans Affairs (VA) disability determination, a Social Security Administration (SSA) disability determination, or a physician’s certification. This provides crucial relief for those facing severe health challenges and student loan debt 2026.
Borrower Defense to Repayment
The Borrower Defense to Repayment discharge provides relief to students whose schools engaged in misconduct, such as making false promises or defrauding students. If approved, the borrower’s federal student loans related to that institution may be discharged. This program has seen significant updates and expansions in recent years, making it an important avenue for those who believe they were misled by their educational institution and are now burdened with student loan debt 2026.
Closed School Discharge
If your school closed while you were enrolled or shortly after you withdrew, you might be eligible for a Closed School Discharge. This discharges 100% of your federal student loans borrowed to attend that school. However, if you completed your program at another school or transferred your credits, you may not be eligible. This provides a safety net for students impacted by unexpected school closures and their associated student loan debt 2026.
Other Forgiveness Opportunities
Beyond these primary programs, other specific forgiveness options exist, such as for nurses, doctors, and lawyers in certain underserved areas, or through state-specific programs. It’s essential to research all potential avenues for relief, as the landscape of student loan debt 2026 is constantly evolving with new initiatives. Always verify eligibility requirements and application processes through official sources.
Strategies for Managing Private Student Loan Debt in 2026
While federal student loans offer a robust array of repayment and forgiveness options, private student loans operate under different rules. These loans, issued by banks, credit unions, and other private lenders, typically lack the flexible repayment plans and forgiveness programs available for federal debt. However, there are still effective strategies for managing private student loan debt 2026.
Refinancing Private Student Loans
One of the most common and effective strategies for private student loans is refinancing. Refinancing involves taking out a new loan, usually from a private lender, to pay off one or more existing private student loans. The goal is typically to secure a lower interest rate, reduce monthly payments, or both. A lower interest rate can save you thousands of dollars over the life of the loan. However, refinancing is often based on your credit score, income, and debt-to-income ratio, meaning those with excellent credit are more likely to qualify for the best rates. It’s a key consideration for anyone looking to optimize their student loan debt 2026.
Before refinancing, consider:
- Interest Rates: Compare offers from multiple lenders to find the lowest possible rate.
- Loan Terms: Shorter terms often mean higher monthly payments but less total interest. Longer terms mean lower monthly payments but more total interest.
- Fees: Be aware of any origination fees or prepayment penalties.
- Co-signer Release: If you have a co-signer, check if the new loan offers a co-signer release option after a certain number of on-time payments.
While refinancing can be highly beneficial for private loans, it’s crucial to remember that refinancing federal loans into a private loan means losing access to federal benefits like IDR plans and forgiveness programs. Therefore, it’s generally not recommended for federal loans unless you are absolutely certain you won’t need those protections.
Communication with Your Lender
If you’re struggling to make payments on your private student loan debt 2026, don’t hesitate to contact your lender. While they don’t offer the same structured programs as the federal government, many private lenders have options for borrowers facing financial hardship. These might include:
- Forbearance: Temporarily pausing payments, though interest will likely continue to accrue.
- Deferment: Similar to forbearance, but often with specific eligibility criteria related to unemployment or in-school status.
- Payment Modifications: Some lenders may be willing to temporarily adjust your payment schedule or amount.
Proactive communication can prevent default and protect your credit score. It’s always better to discuss your situation with your lender before you miss a payment.
Debt Management and Budgeting
Regardless of the type of loan, sound financial management is crucial. Creating a detailed budget can help you understand your income and expenses, identify areas where you can save, and allocate more funds towards your student loan debt 2026. Tools like debt snowball or debt avalanche methods can help you strategically pay down multiple loans. The debt snowball method focuses on paying off the smallest balance first, while the debt avalanche method prioritizes loans with the highest interest rates. Both can be effective, depending on your motivation and financial situation.
Exploring State and Employer-Sponsored Programs
Some states offer their own loan repayment assistance programs (LRAPs) for certain professions, particularly in underserved areas. Additionally, a growing number of employers are beginning to offer student loan repayment as an employee benefit. Researching these less common but potentially impactful options can provide unexpected relief for your student loan debt 2026.
Crucial Tips for Navigating Student Loan Debt in 2026
Effectively managing your student loan debt 2026 requires more than just understanding the available programs; it demands proactive engagement and strategic planning. Here are some crucial tips to help you navigate this complex financial landscape successfully:
Stay Informed and Monitor Your Loans
The student loan environment is subject to frequent policy changes and updates. It is imperative to regularly check official government websites (such as StudentAid.gov) and communicate with your loan servicers. Subscribe to newsletters, follow reputable financial news sources, and periodically review your loan details. Understanding any new legislation or program modifications can significantly impact your repayment strategy for student loan debt 2026. Don’t assume that once you’re on a plan, it won’t change; continuous monitoring is key.
Understand Your Loan Types
As discussed, federal and private loans have fundamentally different rules. Be clear about which type of loans you have. Federal loans offer more protections, including income-driven repayment plans and various forgiveness programs. Private loans, while potentially offering lower interest rates for borrowers with excellent credit, come with fewer safety nets. Knowing your loan types is the first step in determining your eligible options for student loan debt 2026.
Consider Consolidation for Federal Loans
If you have multiple federal student loans, consolidating them into a Direct Consolidation Loan can simplify your repayment by combining them into a single loan with one monthly payment. This can also allow you to access certain income-driven repayment plans and Public Service Loan Forgiveness (PSLF) if your original loans were not Direct Loans (e.g., FFEL Program loans). However, consolidating federal loans can sometimes reset the clock on repayment periods for forgiveness, so evaluate this carefully with regard to your student loan debt 2026.
Utilize Income-Driven Repayment (IDR) Plans Wisely
For many borrowers, IDR plans, especially the SAVE Plan, are the most beneficial way to manage federal student loan debt 2026. They adjust your monthly payment based on your income and family size, making payments more affordable. They also offer a path to forgiveness after a certain number of years. Recertify your income and family size annually, or whenever there’s a significant change, to ensure your payments remain accurate and affordable. Failing to recertify can lead to higher payments or capitalization of interest.
Explore All Forgiveness and Discharge Options
Don’t overlook the various forgiveness and discharge programs available. Whether you qualify for Public Service Loan Forgiveness (PSLF), Teacher Loan Forgiveness (TLF), or a disability discharge, these programs can provide substantial relief. Research the eligibility requirements thoroughly and apply if you meet them. Many borrowers miss out on these opportunities simply because they aren’t aware of them or don’t understand the application process for their student loan debt 2026.
Build an Emergency Fund
Financial stability is paramount. Building an emergency fund can provide a buffer against unexpected expenses or job loss, ensuring you can continue making your student loan payments even during challenging times. Aim for at least three to six months’ worth of living expenses. This fund can prevent you from defaulting on your student loan debt 2026 and protect your credit score.
Seek Professional Advice
If you feel overwhelmed or unsure about the best course of action for your student loan debt 2026, consider consulting a reputable financial advisor or a non-profit credit counseling agency specializing in student loans. They can provide personalized advice, help you understand your options, and assist with application processes. Be wary of companies that promise quick fixes or charge exorbitant fees for services you can do yourself for free.
Avoid Default at All Costs
Defaulting on your student loans can have severe consequences, including damaged credit, wage garnishment, tax refund offset, and even the loss of professional licenses. If you are struggling to make payments, immediately contact your loan servicer to explore forbearance, deferment, or switching to an IDR plan. Proactive communication is essential to avoid the long-term repercussions of default on your student loan debt 2026.
Conclusion: Proactive Management of Student Loan Debt 2026
The landscape of student loan debt 2026 is one of ongoing change and evolving opportunities. While the burden of student loans remains a significant concern for millions, the federal government and various organizations continue to introduce and refine programs designed to offer relief and manageable repayment pathways. From the innovative SAVE Plan to the established Public Service Loan Forgiveness program, borrowers have more tools than ever to navigate their educational debt.
The key to successfully managing your student loan debt 2026 lies in proactive engagement, continuous education, and strategic planning. Understanding the nuances between federal and private loans, exploring all available repayment and forgiveness options, and staying informed about policy changes are not merely suggestions but necessities. Whether you are a recent graduate or a seasoned professional still carrying student debt, taking the time to assess your situation and explore your options can lead to substantial financial benefits and peace of mind.
Remember, you don’t have to tackle your student loan debt 2026 alone. Utilize official resources like StudentAid.gov, consult with reputable financial advisors, and leverage the support networks available. By taking a proactive and informed approach, you can effectively manage your student loans, reduce your financial stress, and pave the way for a more secure financial future. The journey to financial freedom from student loan debt 2026 is achievable with the right knowledge and strategy.
Author