Student Loan Forgiveness 2026: Key Changes & New Federal Relief Programs
Anúncios
The landscape of student loan debt in the United States is constantly evolving, and for millions of Americans, the prospect of student loan forgiveness offers a glimmer of hope. As we look ahead to 2026, it’s crucial to understand the significant changes, new federal relief programs, and updated eligibility criteria that could impact your financial future. Navigating the complexities of federal student aid and debt relief can be daunting, but this comprehensive guide aims to demystify the process, providing you with the knowledge needed to make informed decisions about your student loans.
Anúncios
Understanding the Current State of Student Loan Forgiveness
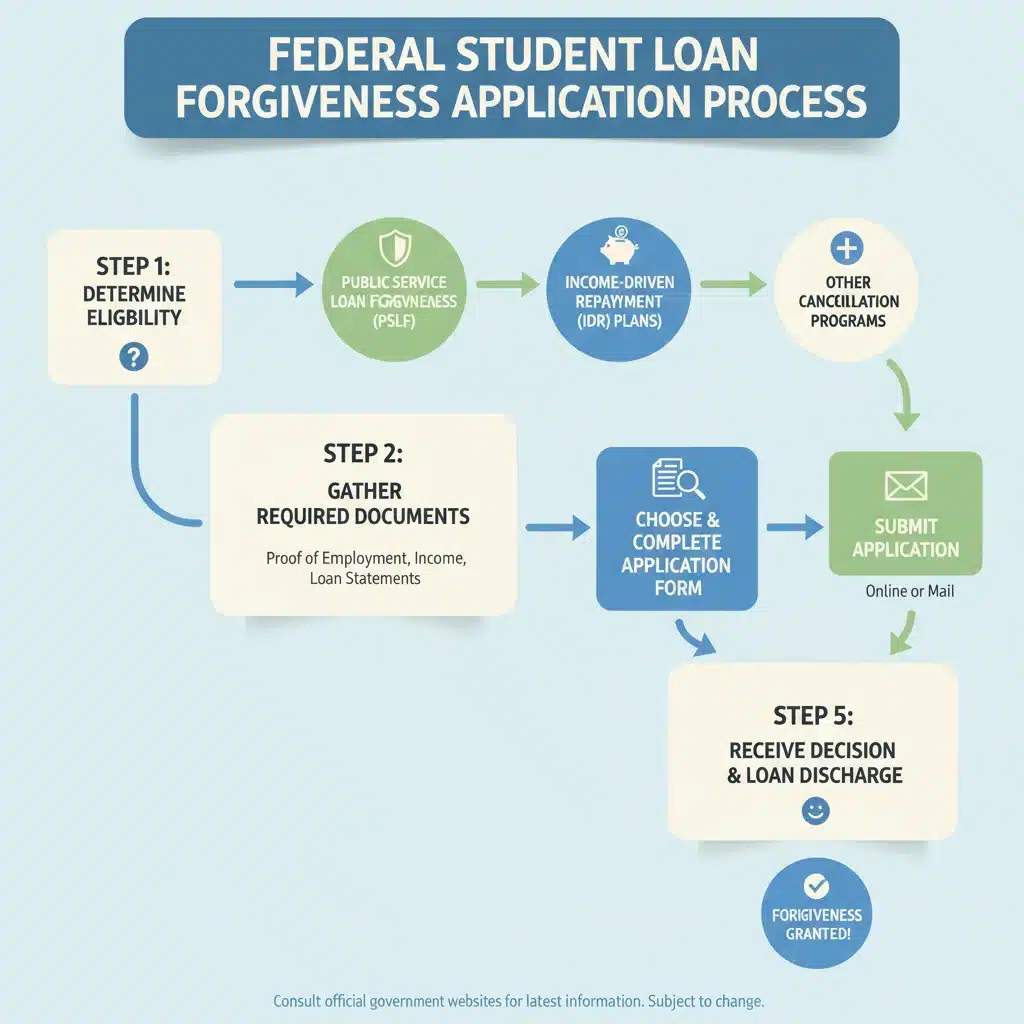
Before diving into what 2026 might bring, it’s essential to grasp the foundation of current student loan forgiveness programs. The federal government has historically offered several avenues for debt relief, primarily through programs like Public Service Loan Forgiveness (PSLF), Income-Driven Repayment (IDR) plans, and specific discharge options for borrowers facing severe circumstances. However, these programs have often been criticized for their complexity, stringent requirements, and low approval rates, leaving many borrowers feeling frustrated and without the relief they desperately need.
The past few years have seen unprecedented changes, largely driven by the economic fallout of the COVID-19 pandemic. The federal student loan payment pause and interest waiver provided temporary relief, but the resumption of payments has reignited the conversation about long-term solutions for student debt. This renewed focus has led to a reevaluation of existing programs and the proposal of new initiatives, setting the stage for potential significant shifts by 2026.
Key Drivers for Change in Student Loan Forgiveness
Several factors are propelling the evolution of student loan forgiveness policies:
Anúncios
- Economic Conditions: Persistent inflation and economic uncertainty continue to impact borrowers’ ability to repay their loans, increasing pressure on policymakers to provide relief.
- Political Landscape: Student loan debt remains a hot-button issue, with various political factions advocating for different approaches, from universal forgiveness to targeted relief. The outcomes of upcoming elections could significantly shape future policies.
- Administrative Reforms: The Department of Education has been actively working to streamline existing programs, particularly PSLF and IDR, to make them more accessible and effective. These administrative changes are likely to continue and expand.
- Legal Challenges: Past attempts at broad student loan forgiveness have faced legal hurdles. Future programs will likely be designed to withstand such challenges, potentially leading to more targeted or administratively robust solutions.
Anticipated Changes in Student Loan Forgiveness 2026
While definitive policies for 2026 are still taking shape, we can anticipate several key areas of change. These changes are likely to focus on expanding eligibility, simplifying application processes, and introducing new mechanisms for debt relief.
Expansion of Eligibility Criteria
One of the most significant anticipated changes is the broadening of eligibility for existing and new forgiveness programs. Historically, many programs have had narrow requirements, leaving out a large segment of borrowers. For student loan forgiveness 2026, we might see:
- Inclusion of More Loan Types: Efforts may be made to include a wider range of federal loans, and potentially even some privately held federal loans, under forgiveness umbrellas.
- Lower Income Thresholds: Income-driven repayment plans, which lead to forgiveness after a certain period, might see adjustments to income thresholds, making it easier for lower and middle-income borrowers to qualify for lower payments and eventual forgiveness.
- Broader Definition of Public Service: The PSLF program could expand its definition of qualifying employment to include more types of non-profit and government work, or even certain essential service roles.
Streamlined Application Processes
The current application processes for many forgiveness programs are notoriously complex and confusing. A major focus for 2026 is expected to be on simplification:
- Automatic Enrollment/Application: For certain eligible borrowers, there might be moves towards automatic enrollment in IDR plans or even automatic forgiveness for those who meet clear, verifiable criteria.
- Consolidated Forms and Portals: A single, user-friendly portal or application form for all federal forgiveness programs could significantly reduce administrative burden and confusion for borrowers.
- Improved Communication: The Department of Education is likely to enhance its communication strategies to better inform borrowers about their eligibility and the steps required to apply for relief.
New Federal Relief Programs on the Horizon
Beyond reforms to existing programs, there’s a strong possibility of new federal relief initiatives emerging by 2026. These could include:
- Targeted Forgiveness Initiatives: Programs specifically designed to help borrowers in particular situations, such as those who attended fraudulent institutions, those with disabilities, or those who have been in repayment for an exceptionally long time.
- Income-Driven Forgiveness Enhancements: Further enhancements to IDR plans, such as shorter repayment periods before forgiveness, or more generous calculations of discretionary income. The SAVE Plan (Saving on a Valuable Education) is a prime example of such an enhancement, and we can expect further refinements or new iterations.
- Debt-to-Income Based Forgiveness: A new approach that ties forgiveness directly to a borrower’s debt-to-income ratio, providing relief to those most burdened by their loans relative to their earning potential.
The SAVE Plan: A Precursor to Future Forgiveness
The recently implemented SAVE Plan is a critical development that offers a glimpse into the future of student loan forgiveness 2026. This income-driven repayment plan significantly reduces monthly payments for many borrowers and offers a faster path to forgiveness, particularly for those with lower original loan balances.
How the SAVE Plan Works
The SAVE Plan builds upon previous IDR plans but offers more generous terms:
- Lower Monthly Payments: It calculates payments based on a smaller percentage of discretionary income (10% for undergraduate loans, 5% for graduate loans, or a weighted average), and significantly increases the amount of income protected from the payment calculation.
- Interest Subsidy: For borrowers whose monthly payment doesn’t cover the accruing interest, the government covers the unpaid interest, preventing loan balances from growing. This is a game-changer for many.
- Faster Forgiveness: Borrowers with original principal balances of $12,000 or less can receive forgiveness after as few as 10 years of payments. The repayment period extends for higher balances, but it’s still often shorter than traditional IDR plans.
Understanding the SAVE Plan is vital because it represents a significant step towards making student loan repayment more manageable and forgiveness more attainable. Future student loan forgiveness 2026 initiatives are likely to draw inspiration from the SAVE Plan’s structure and goals.
Eligibility for Student Loan Forgiveness in 2026: What to Expect
As programs evolve, so too will the criteria for eligibility. To maximize your chances of receiving student loan forgiveness 2026, it’s crucial to stay informed about these potential requirements:
Federal Loan Types
Typically, only federal student loans are eligible for forgiveness programs. This includes Direct Loans (Stafford, PLUS, Consolidation) and sometimes FFEL Program loans if they are consolidated into a Direct Consolidation Loan. Private student loans are almost never eligible for federal forgiveness programs, although some states or private lenders may offer their own relief options.
Income and Family Size
For income-driven repayment plans leading to forgiveness, your Adjusted Gross Income (AGI) and family size are key determinants of your monthly payment and, by extension, your path to forgiveness. Expect these factors to remain central to eligibility calculations.
Employment Type (for PSLF)
If PSLF continues to be a primary avenue for forgiveness, qualifying employment will remain a critical factor. This typically includes full-time employment with a U.S. federal, state, local, or tribal government organization, or a non-profit organization that is tax-exempt under Section 501(c)(3) of the Internal Revenue Code. Anticipate potential expansions to what constitutes ‘qualifying employment’.
Repayment History
Most forgiveness programs require a history of qualifying payments. This means making on-time payments, often under a specific repayment plan (like an IDR plan). The exact number of payments or years in repayment will vary by program, but consistent repayment will likely remain a prerequisite.
Other Specific Conditions
- Total and Permanent Disability (TPD) Discharge: This offers forgiveness for borrowers who are completely and permanently unable to work due to a physical or mental impairment. Eligibility is usually determined by a doctor’s certification, Social Security Administration documentation, or a VA determination.
- Borrower Defense to Repayment: Forgiveness for borrowers who were defrauded by their schools. This program has seen significant reforms and is likely to continue assisting affected individuals.
- Closed School Discharge: If your school closed while you were enrolled or shortly after you withdrew, you might be eligible for loan discharge.
How to Prepare for Student Loan Forgiveness 2026
Even without definitive policies in place, there are proactive steps you can take now to position yourself for potential student loan forgiveness 2026:
1. Understand Your Loan Types
Identify whether your loans are federal or private. Access your loan information through the Federal Student Aid website (studentaid.gov) to determine your loan types, servicers, and current repayment status. This is the foundational step for any debt relief strategy.
2. Consolidate Your Federal Loans (if applicable)
If you have FFEL Program loans or Perkins Loans, consolidating them into a Direct Consolidation Loan can make them eligible for more federal forgiveness programs, including PSLF and IDR plans. Be cautious, however, as consolidation restarts your payment count for forgiveness programs like PSLF, unless you benefit from a temporary waiver or adjustment.
3. Enroll in an Income-Driven Repayment (IDR) Plan
For many, enrolling in an IDR plan like the SAVE Plan is the most direct path to forgiveness. These plans adjust your monthly payment based on your income and family size and can lead to forgiveness of any remaining balance after 10, 20, or 25 years of qualifying payments, depending on the plan and loan type. It also ensures your payments count towards PSLF if you work in public service.
4. Keep Meticulous Records
Maintain thorough records of all your loan documents, payment confirmations, correspondence with your loan servicer, and employment verification forms (especially for PSLF). This documentation will be invaluable if you need to dispute any information or prove your eligibility for forgiveness.
5. Stay Informed and Monitor Official Sources
The student loan landscape is dynamic. Regularly check official sources like the U.S. Department of Education’s Federal Student Aid website (studentaid.gov) for the latest announcements, policy changes, and program updates regarding student loan forgiveness 2026. Avoid relying solely on news headlines or social media for critical information.
6. Contact Your Loan Servicer
Your loan servicer is your primary point of contact for managing your loans. They can help you understand your repayment options, apply for IDR plans, and guide you through the process of submitting necessary documentation. Be persistent and ask detailed questions.
7. Seek Professional Financial Advice
For complex situations, consider consulting with a non-profit credit counselor or a financial advisor specializing in student loan debt. They can provide personalized guidance and help you navigate the best path for your specific circumstances.
The Role of Advocacy and Future Policy Directions
The ongoing debate around student loan debt and forgiveness is heavily influenced by advocacy groups, economic research, and public opinion. By 2026, the cumulative effect of these forces could lead to either more expansive or more targeted relief measures.
Potential for Further Executive Action
Given the legal challenges faced by past broad forgiveness attempts, future executive actions might focus on expanding existing administrative authorities, such as those related to IDR plans or targeted discharges. This approach could offer a more legally robust pathway to providing student loan forgiveness 2026.
Legislative Solutions
While often challenging to achieve, legislative solutions could provide the most comprehensive and permanent reforms to the student loan system. Bipartisan efforts to simplify repayment, reduce interest rates, or create clearer pathways to forgiveness are always a possibility, though political consensus can be difficult to reach.
Addressing the Root Causes of Student Debt
Beyond forgiveness, there’s a growing recognition that addressing the escalating cost of higher education is critical. Future policy discussions around student loan forgiveness 2026 will likely be intertwined with proposals to make college more affordable, potentially through increased federal and state funding for institutions, tuition caps, or reforms to the financial aid system itself. While not direct forgiveness, these measures aim to prevent future generations from accumulating crushing debt.
Common Misconceptions About Student Loan Forgiveness
It’s important to dispel some common myths that can lead to confusion and missed opportunities:
- Myth: All student loans will be automatically forgiven. While some targeted initiatives may offer automatic relief, broad, universal forgiveness is not currently guaranteed and often requires specific actions from borrowers.
- Myth: Private student loans are eligible for federal forgiveness. Federal forgiveness programs almost exclusively apply to federal student loans.
- Myth: Forgiveness is a one-time event. Many programs, especially IDR plans, involve a period of repayment before forgiveness is granted.
- Myth: You don’t need to do anything to get forgiveness. With few exceptions, borrowers must proactively apply, certify employment, or fulfill specific requirements to receive forgiveness.
Impact of Student Loan Forgiveness on the Economy and Individuals
The debate over student loan forgiveness often includes discussions about its broader economic impact. Proponents argue that forgiveness can stimulate the economy by freeing up borrowers’ disposable income, allowing them to save, invest, or spend on other goods and services. It can also reduce stress and improve mental health for millions, enabling them to pursue career paths that might have been unattainable due to debt burdens.
Critics, however, raise concerns about the cost to taxpayers, potential inflationary pressures, and the fairness to those who have already repaid their loans. The ultimate design of student loan forgiveness 2026 programs will likely attempt to balance these competing interests, aiming for targeted relief that provides maximum benefit with manageable economic impact.
Personal Financial Planning Beyond Forgiveness
Even if you qualify for significant student loan forgiveness, it’s crucial to maintain sound financial practices. This includes:
- Budgeting and Saving: Develop a comprehensive budget and work towards building an emergency fund.
- Investing: Once high-interest debt is managed, consider investing for long-term financial growth.
- Credit Management: Monitor your credit score and practice responsible credit use.
- Future Education Planning: If considering further education, explore options for scholarships, grants, and affordable financing to avoid accumulating new debt.
The Road Ahead for Student Loan Borrowers
The journey towards student loan forgiveness 2026 is one of anticipation and adaptation. While the specifics are still unfolding, the direction of policy indicates a continued effort to alleviate the burden of student debt for millions of Americans. Staying informed, organizing your financial documents, and proactively engaging with your loan servicer are your best strategies for navigating this evolving landscape.
The federal government appears committed to making repayment more manageable and forgiveness more accessible through programs like the SAVE Plan and potential new initiatives. By understanding the current framework and preparing for future changes, you can empower yourself to take control of your financial future and work towards the relief you deserve. Keep an eye on official announcements and be ready to act when new opportunities for student loan forgiveness arise.