Social Security 2025: What US Retirees Need to Know About 3.2% COLA
Anúncios
The projected 3.2% Cost-of-Living Adjustment (COLA) for 2025 will directly influence the purchasing power and financial stability of millions of US retirees relying on Social Security benefits.
Anúncios
For millions of Americans, Social Security benefits form the bedrock of their retirement income. Understanding the Recent Updates on Social Security Benefits for 2025: What US Retirees Need to Know About the 3.2% COLA is not just important, it’s essential for sound financial planning. As we approach 2025, the projected Cost-of-Living Adjustment (COLA) is a critical piece of information that will directly impact the daily lives and long-term security of retirees across the nation.
Understanding the Social Security COLA: Its Purpose and Calculation
The Cost-of-Living Adjustment, or COLA, is a vital mechanism designed to protect the purchasing power of Social Security and Supplemental Security Income (SSI) benefits from the erosion caused by inflation. Without regular adjustments, the fixed income of retirees would steadily lose value over time, making it harder to afford essential goods and services. The COLA ensures that benefits keep pace with rising costs, allowing beneficiaries to maintain their standard of living.
Anúncios
The calculation of the COLA is not arbitrary; it follows a specific formula mandated by law. This formula primarily relies on an economic indicator known as the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). The Social Security Administration (SSA) compares the average CPI-W for the third quarter of the current year (July, August, and September) with the average for the third quarter of the previous year. The percentage increase between these two periods determines the COLA for the upcoming year.
The Role of CPI-W in COLA Determinations
The CPI-W is a measure of the average change over time in the prices paid by urban wage earners and clerical workers for a market basket of consumer goods and services. It includes a wide array of items, such as food, housing, apparel, transportation, medical care, recreation, education, and communication. This index is specifically chosen because it is believed to reflect the spending patterns of a significant portion of Social Security beneficiaries.
- Inflationary Gauge: CPI-W acts as the primary barometer for inflation for working-class individuals.
- Quarterly Averages: The SSA specifically looks at third-quarter data to calculate the annual adjustment.
- Impact on Benefits: A higher CPI-W typically leads to a larger COLA, increasing benefits.
It’s important to note that while the CPI-W is the official measure, some critics argue that it may not fully capture the specific spending habits and cost increases experienced by seniors, particularly regarding healthcare expenses. However, for the foreseeable future, the CPI-W remains the benchmark for COLA calculations. Understanding how this index works provides crucial insight into why the COLA might fluctuate from year to year. The 2025 projected 3.2% COLA indicates that the CPI-W has shown a moderate increase, leading to a corresponding adjustment in benefits.
In essence, the COLA is the government’s way of acknowledging that the cost of living doesn’t stay static. By adjusting benefits annually, it aims to provide a continuous level of financial support that retains its value against the backdrop of an evolving economy, offering a degree of stability to retirees.
The Projected 3.2% COLA for 2025: What It Means for Your Pockets
The projection of a 3.2% Cost-of-Living Adjustment for 2025 holds significant implications for millions of Social Security beneficiaries. This percentage increase, if finalized, would translate directly into a boost in monthly payments, offering some relief against ongoing inflationary pressures. While not as high as some recent years, a 3.2% COLA is still a substantial adjustment that can make a tangible difference in a retiree’s budget.
For example, if an individual currently receives $1,800 per month in Social Security benefits, a 3.2% COLA would increase their payment by $57.60, bringing their new monthly benefit to approximately $1,857.60. While this might seem like a modest sum, over the course of a year, it adds up to an additional $691.20, which can be crucial for covering rising costs of living, from groceries to utilities. This adjustment is particularly important for those who rely heavily on Social Security as their primary source of income.
Impact on Average Monthly Benefits
The average Social Security benefit for retired workers is currently around $1,907 per month. With a 3.2% COLA, this average would increase to approximately $1,968.02. This uplift can help offset the increased expenses that retirees face, especially in areas like housing, food, and transportation. It’s a direct response to the economic realities experienced by seniors, aiming to prevent their fixed incomes from being eroded by inflation.
- Increased Purchasing Power: Helps seniors afford essential goods and services.
- Budgetary Relief: Provides additional funds to cover rising living expenses.
- Long-Term Stability: Contributes to maintaining a stable financial outlook throughout retirement.
Beyond the immediate increase in monthly payments, the COLA also affects other aspects of Social Security. For instance, the maximum amount of earnings subject to Social Security taxes typically adjusts with the national average wage index, and the COLA can indirectly influence these figures as well, though the direct calculation is separate. Understanding this projected increase allows retirees to begin adjusting their personal budgets and financial plans for the upcoming year, ensuring they can make the most of their updated benefits. It’s a proactive step in managing retirement finances effectively.
In summary, the 3.2% COLA for 2025 is more than just a number; it represents a tangible increase in financial support for retirees. It is a critical component of ensuring that Social Security continues to provide a safety net that adapts to the economic environment, helping beneficiaries maintain their quality of life.
Key Factors Influencing the 2025 COLA Projection
The projected 3.2% COLA for 2025 is not a random estimate but the result of various economic factors that collectively influence the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). Understanding these underlying drivers provides a clearer picture of why the adjustment is set at this specific level and what might cause future COLA figures to fluctuate. The primary influence is, of course, inflation, but dissecting its various components offers deeper insight.
One of the most significant factors is the overall rate of inflation in the United States economy. When prices for everyday goods and services rise consistently, the CPI-W reflects this trend, leading to a higher COLA. Conversely, periods of low inflation or even deflation result in smaller, or sometimes no, COLA adjustments. For 2025, the 3.2% projection suggests a continued, albeit moderating, inflationary environment compared to the peaks seen in recent years.
Major Economic Indicators and Their Role
Several key economic indicators contribute to the final COLA calculation. These include energy prices, food costs, and housing expenses, which are significant components of the CPI-W. Fluctuations in global oil markets, agricultural yields, and the real estate sector can all have a direct impact on the overall inflation rate and, consequently, the COLA.
- Energy Prices: Volatility in oil and gas markets directly impacts transportation and utility costs.
- Food Costs: Supply chain issues, weather patterns, and global demand affect grocery bills.
- Housing Expenses: Rent and homeownership costs are substantial components of the CPI-W.
Labor market conditions also play a role. A strong labor market with rising wages can contribute to increased consumer spending and, subsequently, higher prices. Conversely, a weakening job market may lead to reduced demand and slower price growth. Geopolitical events and global supply chain disruptions can also create inflationary pressures that ultimately feed into the COLA calculation. For instance, international conflicts or natural disasters can disrupt production and distribution, leading to higher prices for goods.
Therefore, when analyzing the 3.2% COLA for 2025, it’s crucial to consider the broader economic landscape. This projection reflects a period where inflationary pressures are still present but are perhaps easing compared to prior years. The careful monitoring of these factors by economic analysts provides the basis for these projections, offering retirees an early glimpse into their future benefits.
How the 2025 COLA Compares to Previous Years’ Adjustments
Examining the 2025 projected 3.2% COLA in the context of historical adjustments provides valuable perspective for US retirees. Social Security benefits have seen varying levels of COLA increases over the years, reflecting different economic climates. Understanding these comparisons can help beneficiaries gauge the current adjustment’s significance relative to past trends and anticipate its real-world impact on their finances.
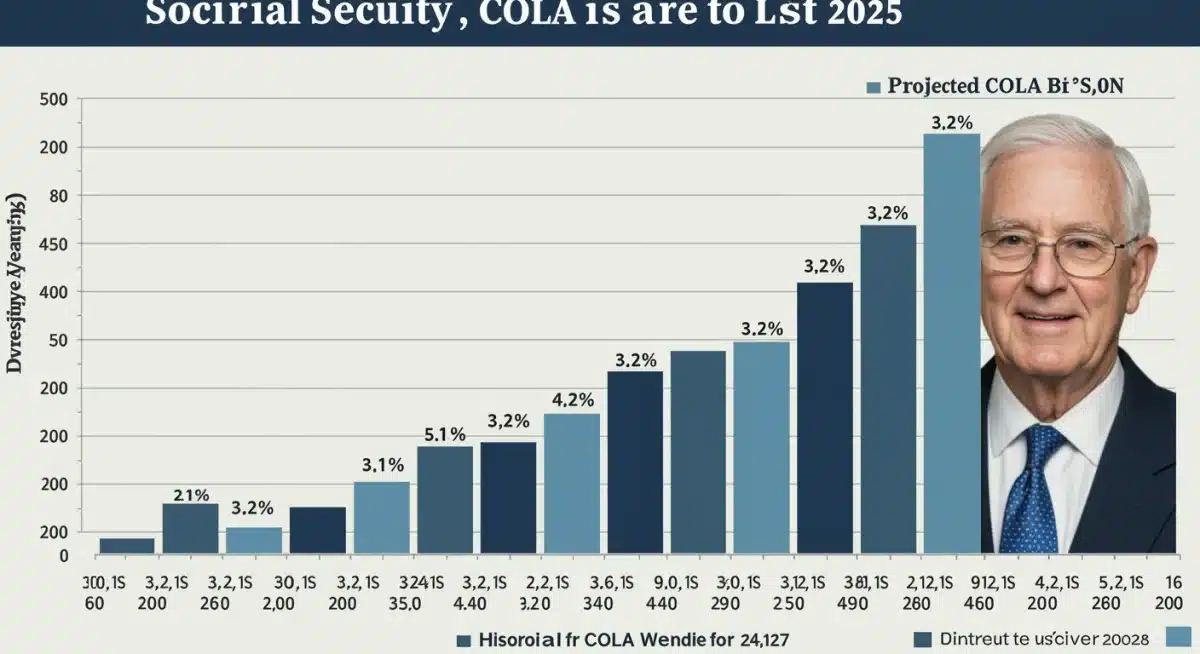
In recent years, COLAs have been notably higher due to a surge in inflation. For example, the 2022 COLA was a substantial 5.9%, followed by an even larger 8.7% for 2023, one of the highest in decades. The 2024 COLA settled at 3.2%, matching the current projection for 2025. These larger adjustments were a direct response to the elevated inflation rates experienced globally and domestically, particularly in the wake of the COVID-19 pandemic and subsequent supply chain disruptions.
Historical COLA Trends and Economic Context
Looking further back, there have been periods of much lower COLAs, and even years with no adjustment at all when inflation was negligible or negative. For instance, in 2010, 2011, and 2016, there were no COLA increases. These periods typically coincided with economic downturns or very stable price environments. The 3.2% projection for 2025 suggests a return to more moderate, though still significant, adjustments compared to the recent peaks.
- High COLA Years: Often linked to periods of rapid inflation (e.g., 2022, 2023).
- Low or No COLA Years: Occurred during periods of low inflation or economic stagnation (e.g., 2010, 2011, 2016).
- 2025 Projection: Indicates a stabilization of inflationary pressures compared to the recent past.
Comparing the 3.2% COLA for 2025 to these historical figures reveals that it falls within a more typical range, though it remains above the average COLA seen over the past two decades. This indicates that while inflation may be cooling, it is still a persistent factor influencing the cost of living for retirees. Understanding this historical context helps beneficiaries appreciate that the COLA is a dynamic adjustment, responsive to the broader economic health of the nation.
In essence, the 2025 COLA is a reflection of a continued commitment to protecting the purchasing power of Social Security benefits, even as the economic landscape shifts. It’s a reminder that while the specific percentage may change, the underlying principle of adjusting benefits to inflation remains constant.
Strategies for Retirees: Maximizing Your Social Security Benefits and Planning for 2025
With the projected 3.2% COLA for 2025, US retirees have an opportunity to fine-tune their financial strategies to maximize their Social Security benefits and ensure long-term financial stability. While the COLA provides an automatic adjustment, proactive planning can help beneficiaries make the most of their increased income and navigate any remaining economic uncertainties. Effective planning goes beyond simply acknowledging the increase; it involves strategic budgeting and informed decision-making.
One primary strategy is to re-evaluate your household budget. With an increase in monthly benefits, even a modest one, you might find opportunities to reallocate funds. This could mean increasing contributions to an emergency fund, paying down high-interest debt, or simply enjoying a bit more discretionary spending. It is crucial to consider how the COLA interacts with other income sources and expenses, especially rising costs in areas like healthcare and housing that might outpace the COLA itself.
Important Considerations for Financial Planning
Beyond budgeting, several other factors warrant attention. For some retirees, the increase in Social Security benefits could potentially impact their Medicare premiums. Medicare Part B premiums are often deducted directly from Social Security checks, and a higher income level could, for some, lead to higher Income-Related Monthly Adjustment Amounts (IRMAA). It’s essential to understand these potential interactions and plan accordingly.
- Review Budget: Adjust spending and savings plans to reflect increased income.
- Medicare Premiums: Be aware of potential impacts on IRMAA for Part B and D.
- Tax Implications: Understand how increased benefits might affect taxable income.
Another key area is understanding the tax implications of increased benefits. While Social Security benefits are generally not fully taxable, a portion of them may be subject to federal income tax if your combined income (adjusted gross income plus non-taxable interest plus half of your Social Security benefits) exceeds certain thresholds. A higher COLA means a higher benefit, which could push some retirees into a higher taxable bracket or increase the taxable portion of their benefits. Consulting with a financial advisor or tax professional can help retirees navigate these complexities and optimize their overall financial picture.
Ultimately, the 2025 COLA is a positive development, but it’s just one piece of the retirement puzzle. By adopting a comprehensive approach to financial planning that incorporates the COLA, retirees can ensure they are well-prepared for the year ahead and maintain a secure financial future.
Potential Challenges and Considerations for Retirees in 2025
While the projected 3.2% COLA for 2025 offers a welcome increase in Social Security benefits, US retirees should also be aware of potential challenges and considerations that could impact their financial well-being. The COLA is designed to offset inflation, but it may not always fully keep pace with specific cost increases that disproportionately affect seniors. A balanced perspective, acknowledging both the benefits and the potential hurdles, is crucial for effective retirement planning.
One significant challenge lies in the rising cost of healthcare. While the CPI-W includes medical care, individual healthcare expenses for seniors can often increase at a rate higher than the general inflation measured by the COLA. This could mean that even with a 3.2% increase in benefits, retirees might find their out-of-pocket medical costs, including prescription drugs, deductibles, and co-pays, consuming a larger portion of their budget.
Navigating Economic Headwinds and Personal Expenses
Another consideration is the potential for increased Medicare Part B premiums. As mentioned previously, higher Social Security benefits can, for some income brackets, lead to higher Income-Related Monthly Adjustment Amounts (IRMAA) for Medicare Part B and Part D. This means that a portion of the COLA increase could be offset by higher premium costs, reducing the net gain in disposable income for some beneficiaries.
- Healthcare Costs: Rising medical expenses may outpace COLA adjustments.
- Medicare Premiums: Potential for higher IRMAA due to increased benefits.
- Other Fixed Costs: Property taxes and insurance might increase independently of COLA.
Furthermore, while the COLA aims to adjust for general inflation, certain localized costs, such as property taxes or specific utility rates, might increase at different rates depending on geographic location. Retirees who own homes might face rising property taxes that are not fully mitigated by the COLA. Similarly, unexpected expenses, such as home repairs or vehicle maintenance, can quickly consume any additional funds provided by the COLA.
Therefore, it is essential for retirees to maintain a robust emergency fund and continuously monitor their personal spending patterns. While the 3.2% COLA is a positive step, it serves as a reminder that comprehensive financial planning must account for a range of potential economic shifts and personal circumstances. Staying informed and adaptable will be key to navigating the financial landscape of 2025.
Future Outlook: What to Expect Beyond 2025 for Social Security and Retirees
Looking beyond the immediate 2025 COLA, US retirees and those approaching retirement should consider the broader future outlook for Social Security. The system faces ongoing demographic and economic challenges, and understanding these long-term trends is vital for comprehensive financial planning. While annual COLAs address immediate inflation, the long-term solvency of Social Security and potential future legislative changes are significant factors to monitor.
One of the most frequently discussed challenges is the solvency of the Social Security trust funds. Projections from the Social Security Administration (SSA) indicate that, without legislative action, the trust funds may only be able to pay a reduced percentage of promised benefits in the coming decades. This is primarily due to an aging population, lower birth rates, and increased life expectancies, leading to a higher ratio of retirees to active workers contributing to the system.
Long-Term Projections and Policy Discussions
While these projections do not mean Social Security will run out of money entirely, they do suggest that future retirees might face benefit reductions if no changes are made. This has led to ongoing discussions among policymakers regarding potential solutions, such as raising the full retirement age, adjusting the COLA calculation method, increasing the Social Security tax rate, or raising the cap on taxable earnings.
- Trust Fund Solvency: Long-term projections indicate potential benefit reductions without intervention.
- Demographic Shifts: Aging population and lower birth rates strain the system.
- Policy Debate: Discussions ongoing about potential legislative reforms.
For retirees, this long-term outlook underscores the importance of not relying solely on Social Security for retirement income. Diversifying income sources through personal savings, investments, and pensions becomes even more critical. Staying informed about legislative proposals and their potential impact is also advisable. Organizations like the AARP and the National Committee to Preserve Social Security and Medicare often provide updates on these policy discussions.
In essence, while the 2025 COLA provides a necessary adjustment for inflation, the future of Social Security requires a broader perspective. Retirees should view their benefits as a foundational component of their financial plan, but not necessarily the sole pillar. Proactive engagement with personal savings and staying abreast of policy developments will be key to ensuring a secure retirement for years to come.
| Key Aspect | Brief Description |
|---|---|
| 2025 COLA Projection | Social Security benefits are projected to increase by 3.2% to combat inflation. |
| COLA Calculation | Determined by the Consumer Price Index for Urban Wage Earners (CPI-W) from Q3. |
| Impact on Retirees | Higher monthly payments, but consider potential Medicare premium adjustments. |
| Financial Planning | Advised to re-evaluate budgets, consider tax implications, and diversify income. |
Frequently Asked Questions About 2025 Social Security Benefits
The projected Cost-of-Living Adjustment (COLA) for Social Security benefits in 2025 is currently estimated at 3.2%. This adjustment aims to help retirees maintain their purchasing power in the face of inflation, ensuring that their benefits keep pace with the rising costs of goods and services.
The COLA is calculated by comparing the average Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) from the third quarter (July, August, September) of the current year with the same period of the previous year. The percentage increase determines the COLA for the upcoming year.
Yes, an increase in Social Security benefits due to the COLA can potentially affect your Medicare Part B and Part D premiums. If your adjusted gross income (AGI) crosses certain thresholds, you might be subject to Income-Related Monthly Adjustment Amounts (IRMAA), leading to higher premiums.
The official announcement for the 2025 Social Security COLA typically occurs in mid-October. This timing allows the Social Security Administration to gather and analyze the necessary CPI-W data from the third quarter before making a final determination and publicizing the adjustment.
Retirees should review their budgets, consider potential impacts on Medicare premiums and taxes, and consult with a financial advisor to optimize their financial planning. It’s also wise to maintain an emergency fund and diversify income sources beyond Social Security for long-term security.
Conclusion
The Recent Updates on Social Security Benefits for 2025: What US Retirees Need to Know About the 3.2% COLA represent a crucial development for millions of Americans relying on these vital payments. The projected 3.2% Cost-of-Living Adjustment underscores the ongoing commitment to preserving the purchasing power of retirees in an evolving economic landscape. While this increase offers a welcome boost to monthly incomes, it also highlights the importance of proactive financial planning. Retirees are encouraged to understand how this COLA impacts their overall budget, potential Medicare premiums, and tax obligations. By staying informed and strategically managing their finances, US retirees can effectively navigate the changes of 2025 and continue to build a secure and stable retirement.