2026 Fed Rate Hikes: Investor’s Guide to Portfolio Protection
Anúncios
The financial landscape is constantly evolving, and for investors, staying ahead of potential shifts is paramount. As we look towards 2026, one of the most significant economic events on the horizon is the anticipated series of interest rate hikes by the Federal Reserve. These adjustments, driven by macroeconomic factors like inflation, employment rates, and global economic stability, have profound implications across all asset classes. Understanding how these 2026 Fed Rates might impact your portfolio is not just about mitigating risks; it’s about identifying opportunities for growth and resilience.
For many, the mention of rising interest rates conjures images of market volatility and uncertainty. However, with a proactive and informed approach, investors can navigate these changes successfully. This comprehensive guide will delve into the intricacies of Federal Reserve policy, dissect the potential ripple effects of higher rates on various investment vehicles, and equip you with actionable strategies to fortify your portfolio. From understanding the Fed’s mandate to re-evaluating your asset allocation, we will explore every facet necessary to thrive in a rising interest rate environment.
Anúncios
The Federal Reserve, often referred to as ‘the Fed,’ plays a pivotal role in the U.S. economy. Its primary mandates are to maintain maximum employment, stable prices, and moderate long-term interest rates. To achieve these goals, the Fed utilizes several monetary policy tools, with the federal funds rate being the most prominent. Changes to this benchmark rate influence everything from consumer lending rates to corporate borrowing costs, ultimately shaping the economic environment for businesses and individuals alike. As we approach 2026, the anticipation of adjustments to these rates necessitates a thorough understanding of their potential impact.
Understanding the Federal Reserve’s Mandate and Tools
Before we can strategize for the 2026 Fed Rates, it’s crucial to grasp the Federal Reserve’s operational framework. The Fed operates under a dual mandate: to achieve maximum sustainable employment and maintain price stability (low and stable inflation). These two objectives often require a delicate balancing act. When inflation rises above the Fed’s target (typically 2%), or when the economy is overheating, the Fed tends to raise interest rates to cool down economic activity. Conversely, during periods of economic slowdown or recession, it lowers rates to stimulate growth.
Anúncios
The primary tool the Fed uses to influence interest rates is the federal funds rate. This is the target rate for overnight lending between banks. While the Fed doesn’t directly control this rate, it influences it through open market operations, where it buys or sells government securities. When the Fed sells securities, it reduces the money supply, pushing interest rates up. When it buys securities, it increases the money supply, pushing rates down.
Other tools include the discount rate (the interest rate at which commercial banks can borrow directly from the Fed), reserve requirements (the amount of funds banks must hold in reserve), and quantitative easing/tightening (large-scale asset purchases or sales). All these tools are deployed strategically to steer the economy toward the Fed’s dual mandate. The projections for 2026 Fed Rates are based on the Fed’s assessment of future economic conditions, including inflation forecasts, GDP growth, and labor market strength.
Why Anticipate Rate Hikes in 2026?
Forecasting economic trends is complex, but several indicators suggest that interest rate hikes could be a reality by 2026. Typically, the Fed considers several key economic factors when deciding on monetary policy:
- Inflation: Persistent inflation above the Fed’s 2% target is a strong signal for rate hikes. If inflationary pressures continue due to supply chain issues, strong consumer demand, or wage growth, the Fed will likely act to curb it.
- Employment: A robust labor market, characterized by low unemployment rates and healthy wage growth, gives the Fed more room to raise rates without fear of stifling job creation.
- Economic Growth (GDP): A strong and sustained Gross Domestic Product (GDP) growth rate indicates an economy that can withstand higher borrowing costs, making rate hikes more palatable.
- Global Economic Conditions: International economic stability, geopolitical events, and global trade dynamics can also influence the Fed’s decisions, as the U.S. economy is intrinsically linked to the global economy.
Analysts and economists often look at forward guidance from the Federal Open Market Committee (FOMC) meetings, speeches by Fed officials, and economic projections to gauge the likelihood and magnitude of future rate changes. While no one has a crystal ball, the consensus around potential 2026 Fed Rates often emerges from these collective analyses. Investors should pay close attention to these signals, as early preparation can significantly impact portfolio performance.
Impact of Rising Interest Rates on Asset Classes
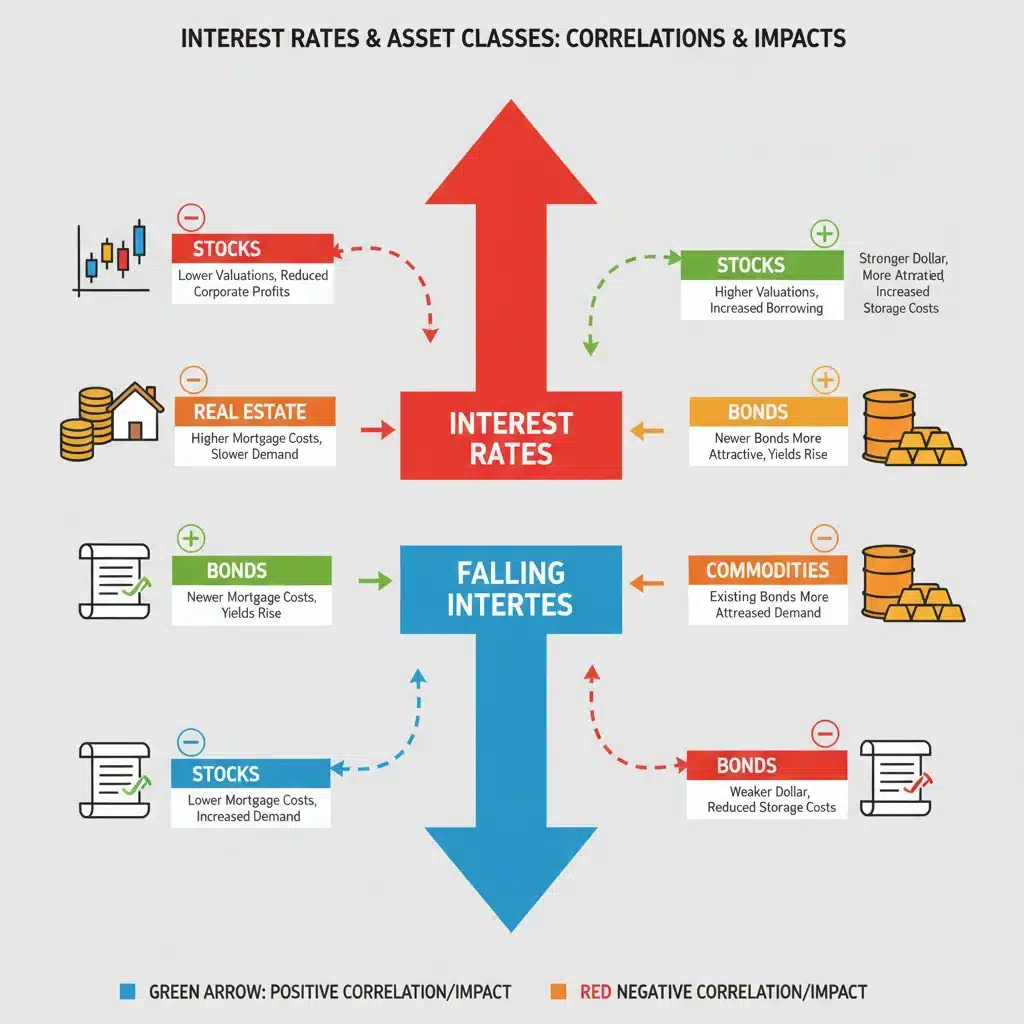
Rising interest rates have a ripple effect across all investment categories. Understanding these impacts is the first step in adjusting your portfolio for the 2026 Fed Rates.
Bonds and Fixed Income
This is perhaps the most directly affected asset class. When interest rates rise, the value of existing bonds with lower coupon rates typically falls. This is because newly issued bonds offer higher yields, making older bonds less attractive. For investors holding bonds to maturity, the impact on principal may be less concerning, but for those who might need to sell before maturity, there’s a risk of capital loss. Shorter-duration bonds tend to be less sensitive to interest rate changes than longer-duration bonds.
Equities (Stocks)
The impact on stocks is more nuanced. Higher interest rates can increase borrowing costs for companies, which can reduce profitability and, consequently, stock prices. Growth stocks, which often rely on future earnings potential and significant borrowing for expansion, can be particularly vulnerable. Conversely, value stocks, which are often more established and less reliant on high growth projections, might fare better. Sectors like financials (banks, insurance companies) can sometimes benefit from higher rates as their lending margins improve, while sectors like real estate (REITs) can be negatively impacted by higher mortgage rates and reduced property demand.
Real Estate
Rising interest rates generally translate to higher mortgage rates, which can cool down the housing market by making homeownership less affordable. This can lead to decreased demand, slower price appreciation, or even price declines in some areas. Commercial real estate can also be affected as borrowing costs for development and acquisition increase, and property yields become less attractive compared to higher-yielding bonds.
Commodities
The relationship between interest rates and commodities is complex. A stronger U.S. dollar, often a consequence of higher interest rates, can make dollar-denominated commodities (like oil and gold) more expensive for international buyers, potentially dampening demand. However, if rate hikes are a response to persistent inflation, commodities might still be seen as a hedge against rising prices, maintaining some demand.
Alternative Investments
Assets like private equity, hedge funds, and cryptocurrencies react differently. Private equity funds might face higher borrowing costs for leveraged buyouts. Cryptocurrencies, often seen as risk assets, could face headwinds as investors gravitate towards safer, yield-bearing assets in a rising rate environment. However, their decentralized nature also means they might not be directly correlated to traditional interest rate movements, presenting both risks and potential diversification benefits.
Strategies to Protect Your Portfolio from 2026 Fed Rates
Preparing for potential interest rate hikes requires a thoughtful and strategic approach. Here are several actionable strategies investors can consider:
1. Re-evaluate Your Asset Allocation
This is the cornerstone of any portfolio adjustment. Review your current mix of stocks, bonds, cash, and alternative investments. Consider reducing exposure to long-duration bonds and increasing allocation to shorter-duration bonds or floating-rate notes, which adjust their interest payments as market rates change. For equities, consider shifting from highly growth-oriented stocks to value stocks or dividend-paying stocks from stable companies that can weather higher borrowing costs.
2. Focus on Quality and Strong Balance Sheets
In an environment of rising rates, companies with strong balance sheets, low debt levels, and consistent cash flows are generally more resilient. They are less reliant on external financing and can absorb higher interest expenses more easily. Look for companies with competitive advantages, stable earnings, and a proven track record of profitability.
3. Consider Dividend Stocks and Value Equities
Dividend-paying stocks, particularly those from mature, financially sound companies, can provide a steady income stream that helps offset potential capital depreciation during market volatility. Value stocks, which are often trading below their intrinsic value, may also offer more stability compared to their growth counterparts, as their valuations are less dependent on aggressive future growth assumptions that can be hampered by higher rates.
4. Explore Shorter-Duration Bonds and Floating-Rate Securities
As mentioned, shorter-duration bonds are less sensitive to interest rate fluctuations. Treasury bills, short-term corporate bonds, and money market funds can offer a safer haven. Floating-rate notes (FRNs) are another excellent option; their interest payments adjust periodically based on a benchmark rate, meaning their yields will rise as interest rates increase, protecting investors from interest rate risk.
5. Diversify Geographically and Across Sectors
Not all economies and sectors react uniformly to interest rate changes. Diversifying your equity holdings across different countries can help mitigate risks specific to the U.S. market. Similarly, diversifying across sectors (e.g., healthcare, utilities, consumer staples) can provide stability, as these sectors are often less cyclical and more resistant to economic downturns caused by higher rates.
6. Real Estate Considerations: REITs and Debt Management
For real estate investors, consider REITs (Real Estate Investment Trusts) that focus on sectors less sensitive to interest rate hikes, such as data centers, cell towers, or industrial properties with long-term leases. If you hold physical real estate, review your mortgage terms. If you have adjustable-rate mortgages (ARMs), consider refinancing into a fixed-rate mortgage before rates climb significantly to lock in lower payments.
7. Alternative Investments for Diversification
Consider alternative investments that may have a low correlation with traditional markets. These could include certain commodities (as inflation hedges), private credit, or infrastructure investments. However, thorough due diligence is essential, as alternatives often come with higher fees and lower liquidity.
8. Maintain Adequate Cash Reserves
Having a healthy cash reserve is always prudent, but especially so in uncertain economic times. Cash provides liquidity for emergencies, allows you to take advantage of market dips (buying opportunities), and offers a safe haven during periods of volatility. While inflation erodes cash value, the flexibility it provides can be invaluable.
9. Review Your Debt
Just as higher rates impact corporate borrowing, they affect personal debt. If you have variable-rate debt (credit cards, certain student loans, HELOCs), prioritize paying it down before rates increase significantly. Locking in fixed rates on any remaining debt can also provide predictability and protection.
Long-Term Perspective and Patience
While preparing for the 2026 Fed Rates is important, it’s equally crucial to maintain a long-term perspective. Market fluctuations are a normal part of investing. Overreacting to short-term forecasts can often lead to suboptimal decisions. Instead, focus on your long-term financial goals, risk tolerance, and investment horizon.
Historically, markets have shown resilience and recovered from various economic challenges, including periods of rising interest rates. A well-diversified portfolio, regularly rebalanced and aligned with your personal financial plan, is the most robust defense against market volatility and economic shifts. Patience and discipline are virtues that often reward investors who stay the course.
The Role of Professional Advice
Navigating the complexities of monetary policy and its impact on your investments can be challenging, even for experienced investors. Consulting with a qualified financial advisor can provide invaluable guidance. A professional can help you:
- Assess your current portfolio’s sensitivity to interest rate changes.
- Develop a personalized strategy tailored to your financial goals and risk profile.
- Identify specific investment opportunities that align with a rising rate environment.
- Stay informed about the latest economic developments and Fed communications.
- Rebalance your portfolio effectively and avoid emotional decision-making.
While this article provides a comprehensive overview, individual circumstances vary widely. A financial advisor can offer tailored advice, ensuring your portfolio is optimally positioned for the anticipated 2026 Fed Rates and beyond.
Conclusion: Proactive Planning for 2026 and Beyond
The prospect of rising Federal Reserve interest rates in 2026 is a significant consideration for every investor. While it presents challenges, it also creates opportunities for those who are prepared and strategic. By understanding the Fed’s role, the potential impacts on various asset classes, and implementing proactive portfolio adjustments, you can not only protect your investments but also position them for growth.
Key takeaways include re-evaluating asset allocation, prioritizing quality companies, considering dividend and value stocks, exploring shorter-duration fixed income, and maintaining diversification. Remember that economic cycles are a natural part of the financial landscape, and while 2026 Fed Rates might bring shifts, a well-thought-out, long-term investment plan remains your most powerful tool. Stay informed, stay diversified, and consider professional guidance to confidently navigate the evolving economic tides.
Author