Advanced Tax-Loss Harvesting for 2026: Maximize Savings and Optimize Your Portfolio
Anúncios
In the dynamic world of investing, smart financial planning extends far beyond simply choosing the right assets. For savvy investors, understanding and implementing advanced tax strategies can significantly impact long-term wealth accumulation. Among these, Tax-Loss Harvesting 2026 stands out as a powerful, yet often underutilized, technique to reduce your annual tax burden and enhance your portfolio’s performance. As we look towards 2026, market conditions, evolving tax laws, and new investment vehicles necessitate a refined approach to this crucial strategy.
Anúncios
This comprehensive guide will delve into the intricacies of advanced Tax-Loss Harvesting 2026, moving beyond the basics to explore sophisticated methods that can save you thousands of dollars annually. We’ll cover everything from understanding the fundamental rules and identifying harvesting opportunities to navigating complex scenarios, integrating AI-driven tools, and aligning this strategy with your broader financial goals. Whether you’re a seasoned investor or just beginning to optimize your tax strategy, the insights provided here will equip you with the knowledge to make informed decisions and maximize your tax efficiency in the coming years.
What is Tax-Loss Harvesting and Why is it Crucial for 2026?
At its core, Tax-Loss Harvesting involves selling investments at a loss to offset capital gains and, potentially, a limited amount of ordinary income. When you sell an investment for less than you paid for it, you realize a capital loss. The IRS allows you to use these losses to offset any capital gains you’ve realized during the year. If your capital losses exceed your capital gains, you can use up to $3,000 of the remaining loss to offset ordinary income per year. Any unused losses can be carried forward indefinitely to offset future capital gains or ordinary income.
The importance of Tax-Loss Harvesting 2026 cannot be overstated. With potential market volatility, fluctuating interest rates, and the ever-present possibility of legislative changes affecting tax codes, being proactive with your tax strategy is paramount. For 2026, understanding the nuances of the tax code and how various investment vehicles interact with harvesting rules will be key to maximizing your benefits. This isn’t just about minimizing taxes; it’s about optimizing your investment portfolio, rebalancing, and positioning yourself for future growth without incurring unnecessary tax liabilities.
Anúncios
Many investors overlook this strategy or only implement it superficially. However, a well-executed Tax-Loss Harvesting 2026 plan can provide a significant advantage, freeing up capital that would otherwise go to taxes and allowing it to be reinvested. This compounding effect over time can lead to substantial wealth creation. By taking a strategic, rather than reactive, approach, you can turn market downturns into tax-saving opportunities.
The primary benefit of Tax-Loss Harvesting 2026 is, of course, the reduction of your tax bill. By offsetting capital gains, you can avoid paying taxes on profits from other investments. This is particularly valuable for high-income earners who face higher capital gains tax rates. Beyond direct tax savings, it also provides an opportune moment to rebalance your portfolio, adjust your risk exposure, and potentially upgrade the quality of your investments. For example, if you sell a struggling stock for a loss, you can immediately reinvest the proceeds into a more promising asset, provided you adhere to the wash-sale rule, which we will discuss in detail.
Furthermore, the psychological benefit of turning a negative (a losing investment) into a positive (tax savings) should not be underestimated. It reinforces disciplined investing and encourages a long-term perspective, even in challenging market conditions. As we navigate towards 2026, economic forecasts and market trends will undoubtedly present both opportunities and challenges. Having a robust Tax-Loss Harvesting 2026 strategy in place will empower you to respond effectively to these dynamics.
Basic Principles and the Wash-Sale Rule: The Foundation of Tax-Loss Harvesting 2026
Before diving into advanced tactics, a solid understanding of the foundational principles, especially the wash-sale rule, is essential for effective Tax-Loss Harvesting 2026. Without this, even the most elaborate strategies can fall apart.
Understanding Capital Gains and Losses
Capital gains and losses are categorized as either short-term or long-term. Short-term gains/losses result from assets held for one year or less, while long-term gains/losses come from assets held for more than one year. This distinction is crucial because short-term capital gains are taxed at your ordinary income tax rates, which are typically higher than long-term capital gains rates. Long-term capital gains currently benefit from more favorable tax rates, often 0%, 15%, or 20%, depending on your income bracket.
When you harvest losses, short-term losses first offset short-term gains, and long-term losses first offset long-term gains. If there are excess losses in one category, they can then be used to offset gains in the other category. For instance, if you have $10,000 in short-term losses and $5,000 in short-term gains, the remaining $5,000 short-term loss can then be used to offset any long-term gains. This netting process is critical for minimizing your overall tax liability.
The Wash-Sale Rule Explained
The wash-sale rule is perhaps the most critical regulation to understand when engaging in Tax-Loss Harvesting 2026. The IRS created this rule to prevent investors from claiming a loss on an investment while simultaneously maintaining an economic interest in that same investment. Specifically, the wash-sale rule states that if you sell an investment for a loss and then buy a substantially identical security within 30 days before or after the sale date, the loss is disallowed.
The 30-day window means a 61-day period in total (30 days before the sale, the day of the sale, and 30 days after the sale). If a wash sale occurs, the disallowed loss is not lost forever; instead, it is added to the cost basis of the newly acquired, substantially identical security. This effectively defers the loss until the new security is sold. While this might seem like a minor setback, it can significantly complicate tax planning and reduce the immediate tax benefits of harvesting.
What constitutes a "substantially identical" security? This is where it gets tricky. For stocks, it generally means the same company’s shares. For mutual funds or ETFs, it could mean funds with very similar investment objectives, holdings, and risk profiles. For example, selling an S&P 500 index ETF for a loss and immediately buying another S&P 500 index ETF from a different provider would likely trigger the wash-sale rule because they are considered substantially identical. However, selling an S&P 500 index ETF and buying a total stock market index ETF might not, as their underlying portfolios are sufficiently different.
Understanding and carefully navigating the wash-sale rule is paramount for successful Tax-Loss Harvesting 2026. Ignorance of this rule can lead to disallowed losses and unexpected tax liabilities. Many advanced strategies revolve around cleverly avoiding wash sales while maintaining desired market exposure.
Advanced Tax-Loss Harvesting Strategies for 2026
Moving beyond the basics, let’s explore sophisticated techniques that can elevate your Tax-Loss Harvesting 2026 efforts and unlock even greater tax savings.
1. The "Buy a Different Fund" Strategy (Pairs Trading for Tax Loss)
This is a classic strategy to circumvent the wash-sale rule while maintaining market exposure. Instead of repurchasing the same or a substantially identical security, you invest the proceeds from the sale of a losing asset into a similar, but not identical, asset. For example, if you sell an S&P 500 index ETF (e.g., SPY) for a loss, you could immediately buy a total stock market index ETF (e.g., VTI) or a different S&P 500 index ETF from another provider (e.g., IVV) if their underlying holdings are considered sufficiently distinct. After 31 days, you can then sell the replacement fund and buy back your original fund if you wish, without triggering a wash sale.
For Tax-Loss Harvesting 2026, this strategy requires careful selection of replacement assets. You need to ensure the replacement fund offers similar exposure to the market segment you want to maintain, but is not deemed "substantially identical" by the IRS. This often involves looking at differences in underlying indices, investment methodologies, or even the fund provider.
2. Utilizing ETFs for Sector-Specific Harvesting
Exchange-Traded Funds (ETFs) offer a powerful tool for advanced Tax-Loss Harvesting 2026. If you hold individual stocks that have incurred losses, you can sell them and immediately reinvest the proceeds into a sector-specific ETF that provides diversified exposure to the same industry. For example, if you sell shares of a struggling tech company, you could buy a broad technology sector ETF. This allows you to harvest the loss while still participating in the potential recovery of the sector, without violating the wash-sale rule (assuming the individual stock is not considered substantially identical to the ETF’s holdings, which is usually the case).
This strategy can also be applied in reverse: selling a losing sector ETF and buying individual stocks within that sector, or another related sector ETF. The key is to manage your exposure and ensure the replacement asset is not substantially identical.
3. "Double Up" Strategy (Pre-emptive Buying)
The "double up" strategy is a more aggressive approach to Tax-Loss Harvesting 2026. If you anticipate selling a security for a loss but want to maintain your position, you can buy additional shares of that security. After 31 days, you then sell the original shares for a loss. Since you purchased the additional shares more than 30 days before the sale, the wash-sale rule does not apply to the original shares, and you effectively "doubled up" your position temporarily. This strategy requires careful timing and a willingness to increase your exposure to a potentially declining asset for a short period.
4. Tax-Loss Harvesting with Bond Funds
While often associated with stocks, Tax-Loss Harvesting 2026 can also be highly effective with bond funds. Interest rate fluctuations can cause bond funds to experience temporary losses, creating harvesting opportunities. Similar to stock funds, you can sell a bond fund for a loss and immediately reinvest in a different bond fund with similar duration and credit quality but from a different issuer or tracking a different index to avoid the wash-sale rule. This strategy is particularly relevant in a rising interest rate environment where bond prices can decline.
5. Harvesting in Taxable vs. Tax-Advantaged Accounts
It’s crucial to remember that Tax-Loss Harvesting 2026 can only be performed in taxable brokerage accounts. Losses in tax-advantaged accounts like 401(k)s or IRAs cannot be used to offset capital gains or ordinary income. However, you can strategically coordinate your harvesting efforts across different account types. For instance, if you have gains in a taxable account, you might prioritize harvesting losses there. Conversely, if you have losses in a tax-advantaged account, it might be an opportunity to rebalance without tax implications, even though you can’t claim the loss.
Integrating Tax-Loss Harvesting into Your Overall Financial Plan for 2026
Effective Tax-Loss Harvesting 2026 is not a standalone event; it should be a continuous process integrated into your broader financial and investment strategy. This holistic approach ensures you’re not just saving taxes in the short term, but also optimizing your portfolio for long-term growth and stability.
Year-Round Monitoring and Opportunistic Harvesting
While many investors focus on harvesting losses at year-end, the most effective approach is to monitor your portfolio year-round. Market downturns can occur at any time, presenting valuable Tax-Loss Harvesting 2026 opportunities. By regularly reviewing your portfolio for unrealized losses, you can be proactive rather than reactive. Tools and platforms that offer automated tax-loss harvesting features can be incredibly beneficial here, as they continuously scan your portfolio for harvesting opportunities and execute trades in compliance with IRS rules.
Rebalancing and Portfolio Optimization
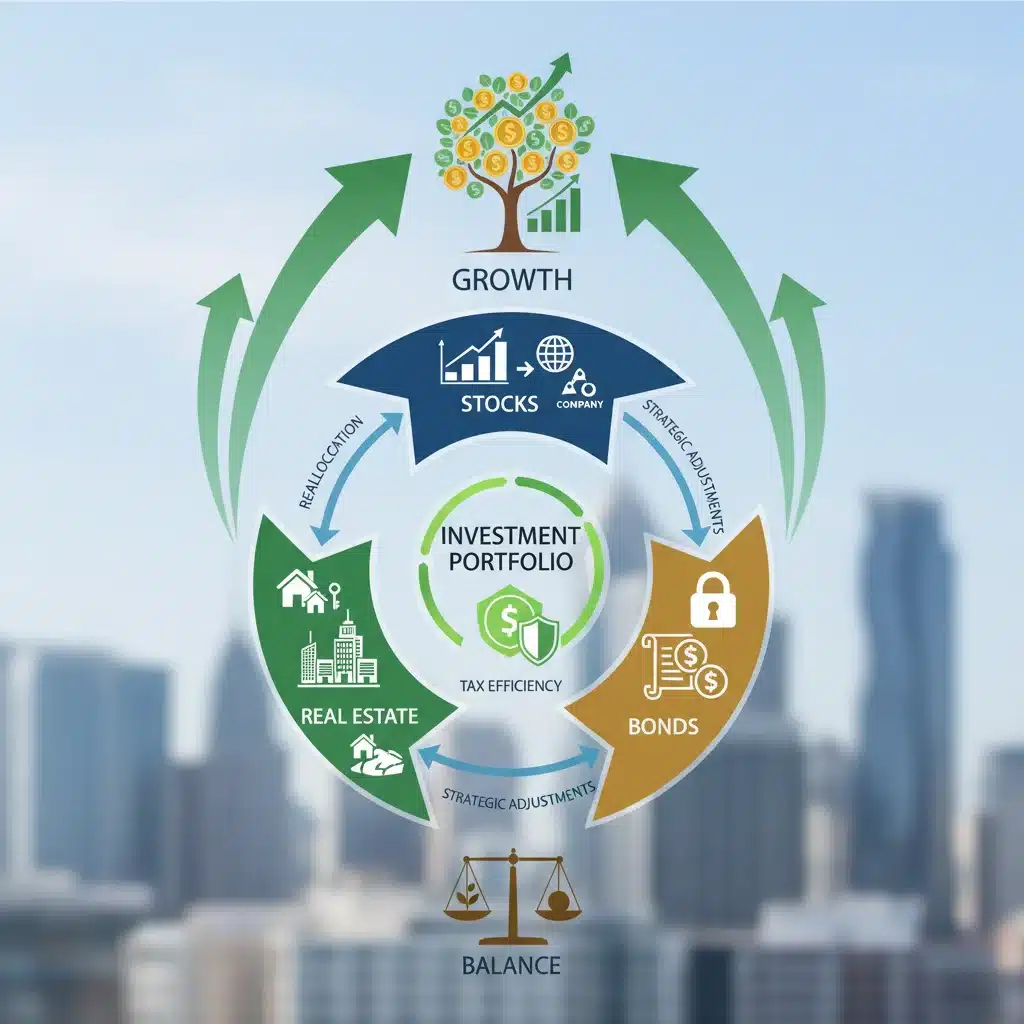
Tax-loss harvesting offers a natural opportunity for portfolio rebalancing. When you sell a losing asset, you can use the proceeds to buy a different, potentially better-performing asset, or to rebalance your asset allocation back to your target weights. This allows you to improve the quality of your portfolio and manage risk without incurring immediate tax consequences on other profitable holdings. For Tax-Loss Harvesting 2026, consider how each harvesting decision aligns with your long-term investment goals and risk tolerance.
Considering Future Tax Brackets and ROTH Conversions
Your current and anticipated future tax brackets play a significant role in advanced Tax-Loss Harvesting 2026. If you expect to be in a lower tax bracket in the future, it might make sense to carry forward losses. Conversely, if you anticipate higher income, maximizing current deductions might be more beneficial. Furthermore, capital losses can be particularly valuable if you are considering a Roth conversion. By using capital losses to offset gains, you can reduce your taxable income, potentially allowing you to convert more traditional IRA funds to a Roth IRA at a lower tax cost.
Estate Planning Implications
For those with substantial portfolios, Tax-Loss Harvesting 2026 can also have estate planning implications. While a step-up in basis at death means that appreciated assets avoid capital gains tax for heirs, depreciated assets do not receive a step-down. Therefore, harvesting losses before death can be a way to utilize those losses while alive, rather than having them disappear upon death. This is a complex area and should be discussed with an estate planning attorney.
Common Pitfalls and How to Avoid Them in Tax-Loss Harvesting 2026
While powerful, Tax-Loss Harvesting 2026 is not without its traps. Being aware of these common mistakes can help you navigate the process smoothly and effectively.
Ignoring the Wash-Sale Rule
As emphasized earlier, violating the wash-sale rule is the most common and detrimental mistake. Always double-check your transactions within the 30-day window before and after selling a security for a loss. This applies across all your accounts, even if held at different brokerage firms. The IRS views you as a single taxpayer, so buying a substantially identical security in a different brokerage account or even in an IRA can trigger the rule. Automated tools can help, but ultimately, the responsibility lies with the investor.
Focusing Solely on Tax Savings Over Investment Goals
While tax savings are a significant benefit, they should not overshadow your primary investment objectives. Selling an asset solely for a tax loss, especially if you believe it has strong long-term potential, might be counterproductive. Always ensure that any harvesting decision aligns with your overall investment strategy and risk tolerance. The goal is to optimize both your tax efficiency and your portfolio’s growth potential for Tax-Loss Harvesting 2026.
Not Tracking Cost Basis Accurately
Accurate record-keeping of your cost basis is fundamental to Tax-Loss Harvesting 2026. If you don’t know your accurate purchase price and sales price, you can’t correctly calculate your gains or losses. Most brokerage firms provide this information, but it’s good practice to cross-reference and maintain your own records, especially if you have transferred assets between firms or engaged in complex transactions like stock splits or mergers.
Failing to Plan for Carryforward Losses
Unused capital losses can be carried forward indefinitely, but many investors fail to track these carryforward losses or use them effectively in subsequent years. Make sure your tax professional is aware of any carryforward losses so they can be applied to future gains or ordinary income, continuing the benefits of Tax-Loss Harvesting 2026.
Over-Harvesting or Under-Harvesting
There’s a sweet spot for Tax-Loss Harvesting 2026. Over-harvesting might mean selling assets you shouldn’t, while under-harvesting means leaving money on the table. The optimal amount depends on your total capital gains, your ordinary income, and your tax bracket. It’s often beneficial to offset all capital gains and then use the additional $3,000 against ordinary income. Beyond that, the benefit is deferred to future years, which is still good, but the immediate impact is capped.
Leveraging Technology and Professional Advice for Tax-Loss Harvesting 2026
In the modern financial landscape, technology and expert guidance are indispensable for executing advanced Tax-Loss Harvesting 2026 strategies.
Robo-Advisors and Automated Harvesting
Many robo-advisors now offer automated tax-loss harvesting as a core feature. These platforms continuously monitor your portfolio, identify harvesting opportunities, and execute trades while adhering to the wash-sale rule by automatically selecting non-substantially identical replacement funds. For investors who prefer a hands-off approach or lack the time for manual monitoring, automated Tax-Loss Harvesting 2026 can be incredibly efficient and effective. They ensure that opportunities are not missed throughout the year, optimizing tax savings over time.
Financial Planning Software and Tools
Beyond robo-advisors, various financial planning software and online tools can assist with Tax-Loss Harvesting 2026. These tools can help you track your cost basis, project your capital gains and losses, and even simulate the impact of different harvesting scenarios on your tax bill. Some advanced tools can analyze your entire financial picture, including investments, income, and deductions, to provide a holistic view of your tax situation.
The Role of a Qualified Financial Advisor and Tax Professional
While technology can automate much of the process, the nuanced decisions and complex scenarios often require the expertise of a qualified financial advisor or tax professional. They can help you:
- Interpret complex tax laws and ensure compliance with the latest regulations for Tax-Loss Harvesting 2026.
- Integrate tax-loss harvesting into a comprehensive financial plan, considering your unique goals, risk tolerance, and time horizon.
- Identify "substantially identical" securities in borderline cases.
- Plan for carryforward losses and optimize their utilization.
- Coordinate harvesting across multiple accounts and with other tax strategies like Roth conversions or charitable giving.
- Provide guidance on estate planning implications of your investment strategy.
A good advisor can provide invaluable insights, preventing costly mistakes and ensuring your Tax-Loss Harvesting 2026 strategy is robust and aligned with your overall wealth management objectives.
Future Considerations and Outlook for Tax-Loss Harvesting Beyond 2026
The landscape of tax policy is constantly evolving, and what holds true for Tax-Loss Harvesting 2026 might shift in subsequent years. Staying informed about potential legislative changes is a critical aspect of long-term tax planning.
Potential Tax Law Changes
Future presidential administrations and congressional compositions could bring about significant changes to capital gains tax rates, ordinary income tax brackets, and even the rules surrounding tax-loss harvesting itself. For instance, there have been discussions in the past about limiting the amount of capital loss that can be carried forward or restricting the types of assets eligible for harvesting. While these are speculative, being aware of such possibilities allows for adaptive planning.
Investors should pay close attention to any proposed legislation that could impact their ability to perform Tax-Loss Harvesting 2026 or alter its effectiveness. This might involve changes to the definition of "substantially identical" securities, adjustments to the $3,000 ordinary income offset limit, or modifications to long-term capital gains rates.
Impact of Market Trends and Economic Cycles
Economic cycles and market trends will continue to create opportunities and challenges for Tax-Loss Harvesting 2026. Periods of market downturns, while unsettling, are often the most fertile ground for harvesting losses. Conversely, prolonged bull markets might offer fewer opportunities for significant losses, shifting the focus more towards managing gains and rebalancing. Understanding these cycles and how they might influence your portfolio is essential for proactive harvesting.
The Rise of Alternative Investments
As alternative investments like cryptocurrencies, private equity, and real estate crowdfunding become more accessible, their tax treatment, particularly concerning losses, will become increasingly relevant. The rules around harvesting losses from these less traditional assets can be complex and may vary. For example, the IRS has issued guidance on cryptocurrency as property, which generally allows for capital loss treatment, but specific rules are still evolving. As we move beyond Tax-Loss Harvesting 2026, staying abreast of these developments will be crucial for investors with diversified portfolios.
Conclusion: Mastering Tax-Loss Harvesting for a Stronger Financial Future in 2026 and Beyond
Mastering Tax-Loss Harvesting 2026 is an invaluable skill for any investor seeking to optimize their financial future. It’s more than just a year-end task; it’s a strategic, ongoing process that, when executed correctly, can lead to substantial tax savings and a more resilient, efficient investment portfolio. By understanding the foundational rules, especially the wash-sale rule, and employing advanced strategies, you can turn market fluctuations into opportunities for tax efficiency.
Integrating tax-loss harvesting into your broader financial plan, utilizing technology for automation and analysis, and seeking professional advice when needed will ensure you are well-positioned to capitalize on every available tax advantage. As we navigate the complexities of the financial markets and evolving tax landscapes towards and beyond 2026, a proactive and informed approach to Tax-Loss Harvesting 2026 will be a cornerstone of successful wealth management. Don’t leave money on the table; empower yourself with these strategies to build a stronger and more tax-efficient financial future.