2026 Federal Reserve Interest Rate Hikes: Investor's Guide
Anúncios
Navigating the 2026 Federal Reserve Interest Rate Hikes: What Investors Need to Know Now
Anúncios
As we move further into the decade, the specter of potential Fed Rate Hikes 2026 looms large on the horizon for investors worldwide. The Federal Reserve, a pivotal institution in the global financial landscape, wields immense power through its monetary policy decisions, particularly regarding interest rates. These decisions reverberate across every asset class, from the most conservative bonds to the most volatile cryptocurrencies, influencing everything from mortgage rates to corporate profitability.
Understanding the nuances of the Federal Reserve’s potential actions in 2026 is not merely an academic exercise; it is a critical component of prudent financial planning and investment strategy. The economic environment is constantly evolving, shaped by a myriad of factors including inflation, employment figures, geopolitical events, and technological advancements. Each of these elements contributes to the Fed’s calculus, making predictions inherently complex yet undeniably necessary for informed investors.
This comprehensive guide aims to equip you with the knowledge and tools needed to navigate the potential landscape of Fed Rate Hikes 2026. We will delve into the underlying economic indicators that typically influence the Fed’s decisions, explore historical precedents, and analyze the potential impacts on various investment portfolios. More importantly, we will outline proactive strategies and considerations that investors can adopt to mitigate risks and potentially capitalize on opportunities arising from a changing interest rate environment.
Anúncios
Whether you are a seasoned institutional investor or an individual managing your retirement savings, the insights provided here will be invaluable. The goal is not to predict the future with absolute certainty, but rather to prepare for various scenarios, fostering resilience and adaptability in your investment approach. Let’s embark on this journey to understand and prepare for the potential Fed Rate Hikes 2026.
Understanding the Federal Reserve’s Mandate and Tools
Before we dissect the potential for Fed Rate Hikes 2026, it’s crucial to grasp the fundamental role and objectives of the Federal Reserve. The Fed operates under a dual mandate from Congress: to foster maximum employment and price stability. These two objectives are often intertwined and can, at times, present policymakers with challenging trade-offs.
The Dual Mandate: Maximum Employment and Price Stability
- Maximum Employment: This doesn’t mean zero unemployment, but rather the highest level of employment that the economy can sustain without generating excessive inflation. The Fed looks at a range of labor market indicators, including the unemployment rate, labor force participation rate, and wage growth.
- Price Stability: This generally refers to keeping inflation at a low and stable level, typically around 2% over the long run, as measured by the Personal Consumption Expenditures (PCE) price index. High inflation erodes purchasing power and creates economic uncertainty, while deflation can stifle economic activity.
Key Monetary Policy Tools
The Federal Reserve employs several tools to achieve its dual mandate, with the federal funds rate being the most prominent. Understanding these tools is key to anticipating Fed Rate Hikes 2026.
- The Federal Funds Rate: This is the target rate for overnight lending between banks. While the Fed doesn’t directly control this rate, it influences it through open market operations. Changes in the federal funds rate cascade through the financial system, affecting other interest rates like those on mortgages, car loans, and credit cards. A hike in this rate makes borrowing more expensive, which can cool down an overheating economy and combat inflation.
- Interest on Reserve Balances (IORB): The Fed pays interest on the reserves that commercial banks hold at the central bank. By adjusting this rate, the Fed can influence banks’ incentive to lend their reserves, thereby affecting the money supply.
- Overnight Reverse Repurchase Agreement (ON RRP) Facility: This tool helps to set a floor for short-term interest rates. Through this facility, the Fed borrows cash from eligible counterparties overnight, offering a security as collateral and paying interest.
- Quantitative Easing (QE) and Quantitative Tightening (QT): These involve the Fed buying or selling large quantities of government bonds and other securities. QE injects liquidity into the financial system and lowers long-term interest rates, while QT (or balance sheet reduction) does the opposite, effectively removing liquidity and potentially pushing long-term rates higher.
When economists and investors discuss potential Fed Rate Hikes 2026, they are primarily referring to an increase in the target range for the federal funds rate. Such a move signals the Fed’s assessment of the economic climate and its intentions to either stimulate or temper economic activity.
Economic Indicators Driving Federal Reserve Decisions for 2026
The Federal Reserve’s decisions are data-dependent, meaning they closely monitor a wide array of economic indicators. For Fed Rate Hikes 2026 to become a reality, certain economic conditions would likely need to persist or emerge. Here are the key indicators the Fed will be watching:
Inflation Data
Inflation is arguably the most critical factor influencing interest rate policy. The Fed’s preferred measure is the Personal Consumption Expenditures (PCE) price index, particularly the core PCE (which excludes volatile food and energy prices). If inflation remains persistently above the Fed’s 2% target, especially due to strong demand or supply-side pressures, the likelihood of Fed Rate Hikes 2026 increases significantly. The Fed aims to prevent inflation from becoming entrenched in consumer and business expectations.
Labor Market Health
A robust labor market, characterized by low unemployment rates, strong job growth, and rising wages, can be a double-edged sword. While indicative of a healthy economy, an overly tight labor market can contribute to inflationary pressures as businesses compete for workers by offering higher pay, which can then be passed on to consumers as higher prices. The Fed will scrutinize:
- Unemployment Rate: A consistently low unemployment rate suggests the economy is operating near full capacity.
- Job Growth: Strong, sustained job creation indicates economic expansion.
- Wage Growth: While higher wages are good for workers, if they outpace productivity gains, they can fuel inflation.
- Labor Force Participation Rate: This metric helps assess the true health and capacity of the labor market.
Gross Domestic Product (GDP) Growth
GDP measures the total economic output of a country. Sustained, strong GDP growth often signals an economy that may be overheating, increasing the risk of inflation. Conversely, slowing GDP growth might give the Fed pause before implementing Fed Rate Hikes 2026, as higher rates could further dampen economic activity and potentially lead to a recession.
Consumer Spending and Confidence
Consumer spending is a major component of GDP. High consumer confidence and robust spending indicate economic strength, but also potential demand-driven inflation. The Fed monitors retail sales, consumer sentiment surveys, and personal consumption expenditures to gauge the health of household finances and spending patterns. A resilient consumer base might allow the Fed more leeway to consider rate increases.
Global Economic Conditions
The U.S. economy does not operate in a vacuum. Global economic growth, geopolitical stability, and supply chain dynamics can all influence domestic inflation and growth. For instance, a global slowdown could weigh on U.S. exports and corporate profits, while international supply shocks could exacerbate inflation. The Fed must consider these external factors when deliberating on Fed Rate Hikes 2026.
Financial Market Stability
While not a primary mandate, financial market stability is a crucial consideration for the Fed. Abrupt or excessive interest rate hikes can sometimes trigger market volatility, credit crunches, or even financial crises. The Fed aims for a ‘soft landing’ – curbing inflation without causing undue market disruption or a recession. This delicate balancing act will be central to any decision regarding Fed Rate Hikes 2026.
Historical Context: Lessons from Past Rate Hike Cycles
Examining previous periods of Federal Reserve interest rate hikes offers valuable insights into potential outcomes for 2026. While history rarely repeats itself exactly, patterns often emerge that can inform investor strategies.
Key Takeaways from Past Cycles
- Impact on Bonds: Generally, rising interest rates lead to a decline in the value of existing bonds, especially longer-duration bonds, as newly issued bonds offer higher yields. This is a fundamental principle to consider for Fed Rate Hikes 2026.
- Equity Market Volatility: Stock markets often experience increased volatility during rate hike cycles. Sectors sensitive to interest rates, like housing and utilities, tend to be more affected. Growth stocks, which rely on future earnings discounted at higher rates, can also face headwinds.
- Sector Rotation: Investors often rotate into sectors that perform better in a rising rate environment, such as financials (banks benefit from wider net interest margins) and value stocks.
- Strength of the Dollar: Higher interest rates typically attract foreign capital, strengthening the U.S. dollar. This can make U.S. exports more expensive but imports cheaper.
- Economic Slowdown Risk: Aggressive rate hikes can sometimes tip the economy into a recession, as borrowing becomes more expensive for businesses and consumers, slowing investment and spending.
The specific context of 2026 will be unique, but these historical tendencies provide a framework for anticipating market reactions to potential Fed Rate Hikes 2026.
Potential Impacts of Fed Rate Hikes 2026 on Your Portfolio
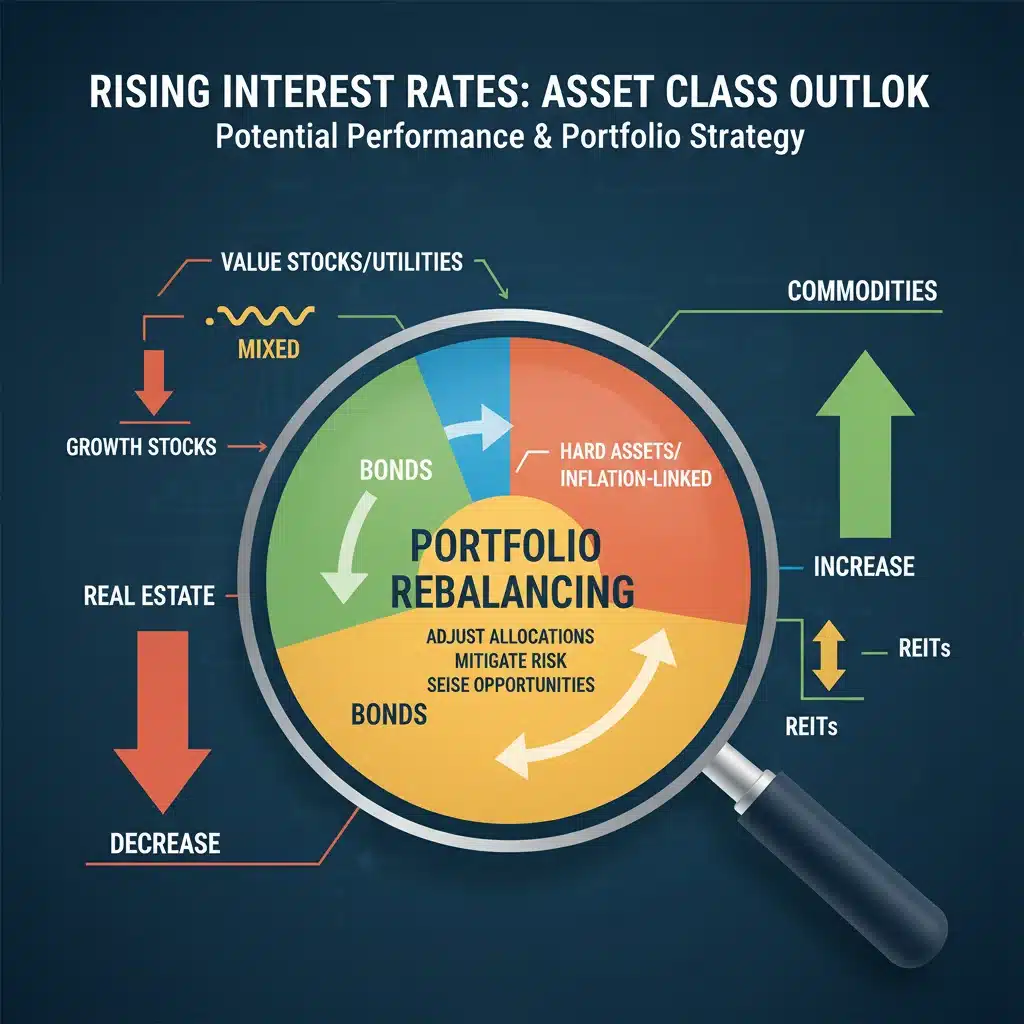
A change in the Federal Reserve’s monetary policy is a seismic event for financial markets. Here’s a breakdown of how potential Fed Rate Hikes 2026 could affect different asset classes within your investment portfolio.
Bonds and Fixed Income
This is perhaps the most directly impacted asset class. When interest rates rise, the appeal of newly issued bonds with higher yields increases, making older bonds with lower yields less attractive. This causes the market value of existing bonds to fall. Longer-duration bonds are more sensitive to interest rate changes than shorter-duration bonds. Investors holding a significant portion of their portfolio in long-term fixed income should be particularly attentive to the implications of Fed Rate Hikes 2026.
Equities (Stocks)
The impact on stocks is more nuanced:
- Growth Stocks vs. Value Stocks: Growth stocks, often in technology, derive a larger portion of their value from future expected earnings. Higher discount rates (due to rising interest rates) make those future earnings less valuable today, potentially impacting growth stock valuations. Value stocks, which are often mature companies with stable earnings and dividends, may be more resilient or even perform better.
- Corporate Borrowing Costs: Companies that rely heavily on debt financing will face higher borrowing costs, which can reduce profitability and impact earnings per share.
- Consumer Spending: Higher interest rates can lead to increased mortgage and loan payments for consumers, potentially reducing discretionary spending, which can affect companies in retail and consumer discretionary sectors.
- Sector Performance: As mentioned, financial stocks (especially banks) can benefit from wider net interest margins. Utilities and real estate investment trusts (REITs) are often sensitive to interest rates due to their debt loads and dividend-paying nature, and may face headwinds.
Real Estate
Rising interest rates generally cool the real estate market. Higher mortgage rates make homeownership less affordable, potentially reducing demand and slowing price appreciation. For commercial real estate, higher borrowing costs can impact development projects and property values. Investors in REITs or direct real estate holdings should monitor these trends closely in anticipation of Fed Rate Hikes 2026.
Commodities
The relationship between interest rates and commodities is complex. A stronger dollar, often a consequence of rising U.S. interest rates, can make dollar-denominated commodities (like oil and gold) more expensive for foreign buyers, potentially dampening demand. However, if rate hikes are necessitated by strong economic growth, demand for industrial commodities could remain robust. Gold, often seen as an inflation hedge, might face pressure from higher real interest rates.
Alternative Investments (e.g., Private Equity, Hedge Funds)
These assets are also susceptible. Private equity deals often rely on debt financing, so higher interest rates can increase the cost of acquisitions and reduce returns. Hedge fund strategies vary widely, but those employing leverage or exposed to interest-rate sensitive assets will need to adapt to the changing environment.
Strategies for Investors Amidst Potential Fed Rate Hikes 2026
Proactive planning is essential. Here are several strategies investors can consider to prepare their portfolios for potential Fed Rate Hikes 2026.
1. Re-evaluate Your Bond Holdings
If you have a significant allocation to fixed income, consider reducing your exposure to long-duration bonds, which are most sensitive to rising rates. Instead, explore:
- Short-Duration Bonds: These bonds mature sooner, allowing you to reinvest at higher rates more quickly.
- Floating-Rate Notes: The interest payments on these bonds adjust with market rates, offering protection against rising rates.
- Treasury Inflation-Protected Securities (TIPS): The principal value of TIPS adjusts with inflation, providing a hedge against rising prices.
- Bond Ladders: Staggering bond maturities allows you to reinvest maturing bonds at prevailing higher rates.
2. Review Your Equity Portfolio
Consider a tilt towards sectors that historically perform well in rising rate environments:
- Financials: Banks often benefit from higher interest rates as their net interest margins (the difference between what they earn on loans and pay on deposits) tend to widen.
- Value Stocks: These companies often have stable earnings, pay dividends, and are less dependent on future growth projections, making them potentially more resilient.
- Companies with Strong Balance Sheets: Businesses with low debt levels will be less impacted by higher borrowing costs.
- Dividend-Paying Stocks: While bond yields rise, solid dividend stocks can still offer attractive income streams, especially if their dividend growth is consistent.
Conversely, be cautious with highly leveraged companies or growth stocks with stretched valuations that rely heavily on low discount rates for their perceived value.
3. Diversify Beyond Traditional Assets
Diversification remains a cornerstone of sound investment. Consider alternative asset classes that may offer different risk-return profiles:
- Commodities: Certain commodities can act as an inflation hedge, though their performance can be volatile.
- Real Assets: Investments in infrastructure, timberland, or farmland can sometimes offer stability and inflation protection.
- Private Markets: Private equity, private debt, and venture capital, while less liquid, can offer uncorrelated returns, though they come with their own set of risks and require careful due diligence.
4. Maintain Liquidity
Having sufficient cash or highly liquid assets can provide flexibility. It allows you to cover unexpected expenses without selling assets at potentially unfavorable times and positions you to take advantage of new investment opportunities that may arise from market dislocations caused by Fed Rate Hikes 2026.
5. Focus on Quality and Fundamentals
In uncertain times, fundamental analysis becomes even more critical. Invest in companies with strong balance sheets, consistent cash flow, competitive advantages, and proven management teams. These ‘quality’ companies are often better positioned to weather economic shifts and higher interest rates.
6. Consider Dollar-Cost Averaging
Instead of trying to time the market, which is notoriously difficult, consider investing a fixed amount regularly. This strategy, known as dollar-cost averaging, helps mitigate the risk of investing a lump sum at a market peak and allows you to buy more shares when prices are lower.
7. Stay Informed and Adaptable
The economic landscape is dynamic. Continuously monitor economic indicators, Federal Reserve communications, and market reactions. Be prepared to adjust your strategy as new information becomes available. Flexibility is a key attribute of successful investors, especially when anticipating significant policy shifts like potential Fed Rate Hikes 2026.
The Role of Inflation Expectations and the Neutral Rate
Beyond the immediate data, the Federal Reserve also pays close attention to inflation expectations and its assessment of the ‘neutral rate’ of interest. These concepts are crucial for understanding the long-term trajectory of monetary policy and the likelihood of Fed Rate Hikes 2026.
Inflation Expectations
If businesses and consumers expect inflation to remain high, they may adjust their behavior (e.g., demanding higher wages, raising prices), which can create a self-fulfilling prophecy. The Fed actively tries to anchor inflation expectations at its 2% target. If these expectations become unanchored and start to drift higher, the Fed will be more inclined to raise rates to bring them back down.
The Neutral Rate (R*)
The neutral rate of interest (often denoted as R*) is the theoretical short-term interest rate that neither stimulates nor constrains economic growth. It’s the rate at which the economy is at full employment and inflation is stable at the Fed’s target. The Fed’s estimate of the neutral rate is not fixed; it can change over time due to factors like productivity growth and demographics. If the current federal funds rate is below the neutral rate, it suggests monetary policy is still accommodative, giving the Fed room to raise rates without necessarily slowing the economy too much. The Fed’s assessment of where R* stands will heavily influence its decision-making for Fed Rate Hikes 2026 and beyond.
Potential Scenarios for 2026 and Beyond
While no one has a crystal ball, we can outline a few potential scenarios that could lead to or prevent Fed Rate Hikes 2026:
Scenario 1: Persistent Inflation and Strong Growth
If inflation remains stubbornly above the 2% target, driven by robust consumer demand, a tight labor market, and perhaps ongoing supply-side challenges, while economic growth remains solid, the Fed would likely continue or initiate a series of rate hikes. In this scenario, investors would need to be well-positioned with strategies outlined above.
Scenario 2: Economic Slowdown or Recession
Conversely, if economic growth decelerates significantly, or if the economy enters a recession, the Fed might pause or even reverse its rate hike stance. In such a situation, the focus would shift from combating inflation to supporting economic recovery. Bonds might perform better, and defensive stocks could gain favor.
Scenario 3: Disinflation and Moderate Growth
A ‘goldilocks’ scenario where inflation gradually returns to the 2% target without a significant economic downturn. In this case, the Fed might maintain rates at a certain level or implement only minor adjustments. Market reactions would be less dramatic, and investors could focus on long-term growth opportunities.
It’s important to remember that the Fed’s policy is often a reaction to evolving data, not a predetermined path. Therefore, continuous monitoring of economic reports and Fed communications is paramount for investors preparing for Fed Rate Hikes 2026.
Conclusion: Preparing for the Future of Interest Rates
The prospect of Fed Rate Hikes 2026 is a significant consideration for any investor. The Federal Reserve’s monetary policy decisions have far-reaching implications, influencing asset valuations, borrowing costs, and the overall economic trajectory. While predicting the exact timing and magnitude of future rate adjustments is impossible, understanding the underlying drivers and potential impacts is within every investor’s grasp.
By focusing on the Fed’s dual mandate, closely monitoring key economic indicators like inflation and employment, and drawing lessons from historical rate hike cycles, investors can build a more resilient and adaptable portfolio. Strategies such as re-evaluating bond holdings, tilting equity exposure towards value and financial sectors, diversifying into alternative assets, and maintaining liquidity can help mitigate risks and uncover opportunities.
Ultimately, successful investing in an environment of potential Fed Rate Hikes 2026 hinges on a combination of informed decision-making, proactive planning, and a commitment to continuous learning. Stay disciplined, stay diversified, and stay informed, and you will be better equipped to navigate whatever the future holds for interest rates and the broader economy.
The journey through the financial markets is rarely smooth, but with careful preparation and a clear understanding of the forces at play, investors can position themselves for long-term success, even in the face of evolving monetary policy. The time to prepare for Fed Rate Hikes 2026 is now.