Interest Rate Forecast 2026: Fed Hikes & US Financial Impact
Anúncios
The 2026 interest rate forecast anticipates potential Fed hikes of 0.75%, significantly influencing mortgage rates, consumer borrowing costs, and returns on savings accounts across the United States.
Anúncios
Understanding the interest rate forecast 2026 is crucial for every American, as expected Fed hikes of 0.75% could reshape everything from your mortgage payments to the returns on your savings. This article delves into the potential ramifications, offering insights to help you navigate the evolving financial landscape.
Anúncios
Understanding the Federal Reserve’s Role in Rate Hikes
The Federal Reserve, often simply called the Fed, plays a pivotal role in steering the U.S. economy. Its decisions on interest rates directly influence the cost of borrowing and the returns on savings, affecting millions of households and businesses. When the Fed raises rates, it’s typically a strategic move to curb inflation or cool down an overheating economy.
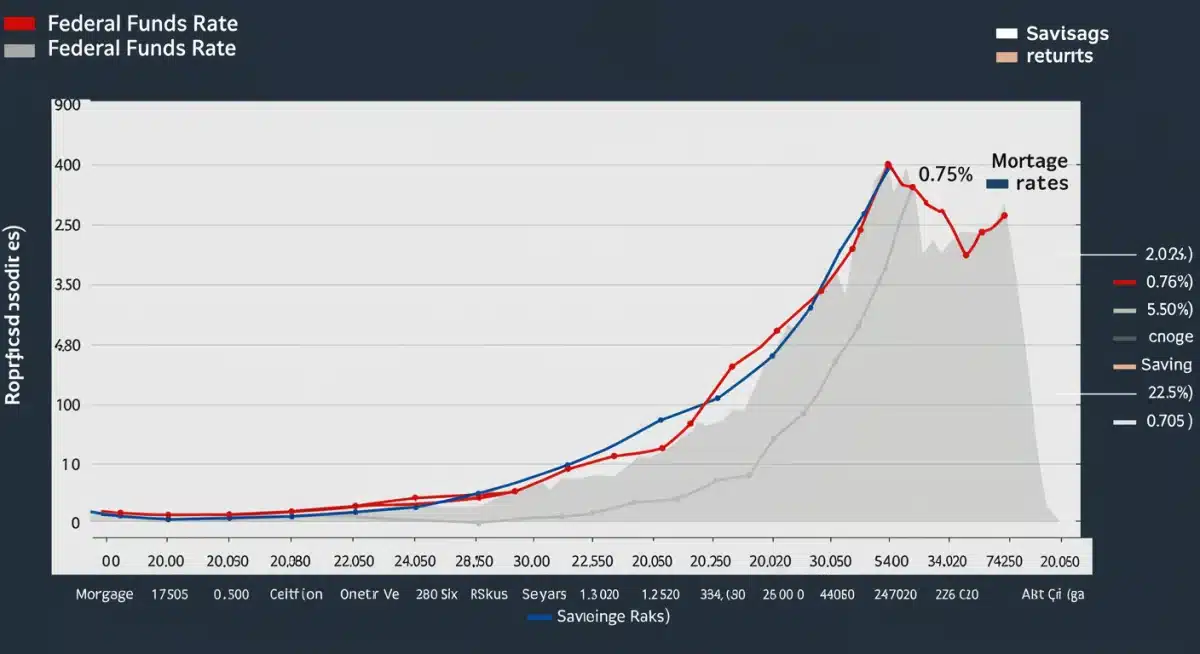
The primary tool the Fed uses is the federal funds rate, which is the target rate for overnight lending between banks. While not directly what consumers pay, changes to this rate ripple through the entire financial system, impacting everything from prime rates to long-term mortgage rates. A projected 0.75% hike, as discussed for 2026, signals a significant shift in monetary policy aimed at achieving specific economic objectives.
The Mechanism of Rate Adjustments
- Open Market Operations: The Fed buys or sells government securities to influence the money supply and, consequently, the federal funds rate.
- Discount Rate: This is the interest rate at which commercial banks can borrow money directly from the Fed.
- Reserve Requirements: The amount of funds banks must hold in reserve, though less frequently adjusted, also impacts lending capacity.
These mechanisms collectively allow the Fed to implement its monetary policy. When the Fed signals a hike, it’s often a pre-emptive measure, attempting to guide the economy toward a desired state without causing undue shock. The 0.75% increase in 2026 would be a notable adjustment, reflecting the Fed’s assessment of future economic conditions and inflationary pressures.
In essence, the Fed acts as the economy’s thermostat, adjusting rates to maintain a stable and healthy environment. Their decisions are not made lightly and involve extensive analysis of economic indicators, labor markets, and inflation trends. Understanding this foundational role is key to grasping the broader implications of any future rate adjustments.
Direct Impact on Mortgage Rates for Homeowners and Buyers
For many Americans, the most immediate and tangible effect of a Fed interest rate hike is felt in the housing market. A 0.75% increase in the federal funds rate will almost certainly translate into higher mortgage rates, impacting both prospective homebuyers and those with adjustable-rate mortgages (ARMs).
When the cost of borrowing for banks increases, they pass those costs onto consumers. For fixed-rate mortgages, this means new borrowers will face higher monthly payments. For instance, a small percentage increase can add hundreds of dollars to a monthly payment over the life of a loan, significantly reducing purchasing power and potentially slowing down the housing market.
Adjustable-Rate Mortgages (ARMs) and Refinancing
- Increased Monthly Payments: ARM holders will see their payments rise, potentially impacting household budgets.
- Refinancing Challenges: Homeowners looking to refinance their existing mortgages may find higher rates less appealing or even prohibitive, especially if their current rate is significantly lower.
- Reduced Affordability: Higher rates reduce the maximum loan amount buyers can afford, leading to a decrease in demand and potentially a cooling of home prices in some markets.
The ripple effect extends beyond monthly payments. Higher mortgage rates can also cool down a hot housing market, as fewer buyers can afford the increased costs. This might lead to longer selling times and a more balanced market between buyers and sellers, though significant price drops are not always a direct consequence of moderate rate increases.
Therefore, anyone considering buying a home or managing an ARM should closely monitor the 2026 interest rate forecast. Proactive planning, such as locking in a fixed rate before potential hikes, could be a prudent strategy for those in a position to do so.
The Effect on Savings Accounts and Investment Returns
While higher interest rates can be a challenge for borrowers, they often present a silver lining for savers. When the Fed raises rates, banks typically respond by increasing the interest they pay on savings accounts, certificates of deposit (CDs), and money market accounts. A 0.75% hike could mean more attractive returns for those holding cash.
This is particularly beneficial for individuals who rely on passive income from their savings or those building an emergency fund. The increased yield can help offset inflation and provide a greater incentive to save. However, it’s important to note that the increase in savings rates may not always perfectly mirror the Fed’s hike, as banks also consider their own lending opportunities and competitive landscape.
Opportunities for Savers and Investors
- Enhanced Savings Yields: Standard savings accounts, high-yield savings accounts, and money market accounts will likely offer better returns.
- Attractive CD Rates: Certificates of Deposit become more appealing, providing a fixed return for a set period, which can be advantageous in a rising rate environment.
- Bond Market Dynamics: New bonds issued after a rate hike will offer higher yields, making them more attractive to investors. Existing bond prices, however, may decline.
For investors, the impact is more nuanced. While bond yields may rise, existing bond portfolios could see a decrease in value. Equity markets can also react to rate hikes, as higher borrowing costs for businesses can impact profitability and growth prospects. Companies that are heavily reliant on debt might face increased financial pressure.
Savers and investors should therefore review their portfolios and financial strategies in light of the projected 2026 interest rate forecast. Moving funds to higher-yielding accounts or adjusting investment allocations could be beneficial to maximize returns and mitigate potential risks.
Broader Economic Implications of a 0.75% Rate Hike
A 0.75% federal funds rate hike in 2026 would send significant ripples throughout the U.S. economy, extending beyond just mortgages and savings. These increases are designed to influence overall economic activity, primarily by making borrowing more expensive and thus cooling demand.
One of the main goals of raising rates is to combat inflation. By increasing the cost of money, the Fed aims to reduce consumer spending and business investment, which can help to bring down prices. However, this strategy carries the risk of slowing economic growth too much, potentially leading to a recession.
Impact on Consumer Spending and Business Investment
Higher interest rates affect consumer spending in several ways. Not only do mortgage payments increase, but so do the interest rates on credit cards, auto loans, and other forms of consumer credit. This reduces disposable income and can lead to a decrease in overall consumer demand.
- Reduced Consumer Demand: Higher borrowing costs deter consumers from taking on new debt for large purchases.
- Decreased Business Investment: Companies face higher costs for loans to fund expansion, equipment purchases, and research and development, potentially slowing job creation.
- Strengthening U.S. Dollar: Higher rates can attract foreign investment, increasing demand for the dollar and making imports cheaper but exports more expensive.
For businesses, higher borrowing costs can directly impact their profitability and expansion plans. Small businesses, in particular, might find it harder to secure affordable loans, potentially hindering their growth and ability to hire. Larger corporations may also reconsider investment projects if the cost of capital becomes too high.
The broader economic implications are complex and interconnected. While the Fed aims for a ‘soft landing’ – curbing inflation without triggering a recession – achieving this balance is a delicate act. The 2026 interest rate forecast suggests a period where economic adjustments will be closely watched by policymakers, businesses, and consumers alike.
Strategies for Consumers to Navigate Rising Rates
With the prospect of a 0.75% Fed hike in 2026, consumers should proactively consider strategies to protect their finances and even capitalize on the changing environment. Being prepared can make a significant difference in managing personal budgets and investment portfolios.
One primary strategy involves evaluating existing debt. For those with variable-rate debt, such as certain credit cards or lines of credit, paying down balances aggressively before rates rise can save a considerable amount in interest payments. Consolidating high-interest debt into a fixed-rate personal loan, if available at a competitive rate, could also be a wise move.
Financial Planning in a Rising Rate Environment
- Prioritize Debt Reduction: Focus on paying off high-interest, variable-rate debts first to minimize increased costs.
- Review Mortgage Options: If you have an ARM, consider refinancing to a fixed-rate mortgage if current rates are still favorable.
- Boost Savings: Take advantage of potentially higher yields on savings accounts, CDs, and money market accounts.
- Reassess Investment Portfolios: Consult with a financial advisor to ensure your investments are aligned with a rising interest rate environment.
For those planning major purchases requiring financing, such as a home or a car, acting sooner rather than later might secure a lower interest rate. However, this decision should always be weighed against personal financial stability and market conditions. Rushing into a significant financial commitment without thorough consideration can be risky.
Moreover, building a robust emergency fund becomes even more critical in an environment of rising costs. Having readily available cash can provide a buffer against unexpected expenses or increased debt payments. Diversifying investments and seeking professional financial advice are also key components of navigating these economic shifts successfully.
Historical Context and Future Outlook for Interest Rates
To fully appreciate the significance of the 2026 interest rate forecast, it’s helpful to look at historical patterns of Fed policy. The Federal Reserve has a long history of adjusting rates in response to economic cycles, periods of inflation, and recessions. Understanding these past actions can provide clues about potential future trajectories.
Historically, aggressive rate hikes have often been employed to combat persistent inflation, even at the risk of slowing economic growth. Conversely, during economic downturns, the Fed typically lowers rates to stimulate borrowing and investment. The anticipated 0.75% hike in 2026 suggests the Fed is likely prioritizing inflation control or aiming to normalize rates after a period of lower borrowing costs.
Factors Influencing Future Rate Decisions
Several key economic indicators will continue to shape the Fed’s decisions beyond 2026:
- Inflation Data: The Consumer Price Index (CPI) and Personal Consumption Expenditures (PCE) will be critical.
- Employment Figures: Unemployment rates, wage growth, and job creation reports will heavily influence policy.
- Economic Growth (GDP): The strength of the overall economy, as measured by GDP, will play a role.
- Global Economic Conditions: International economic stability and events can also factor into the Fed’s outlook.
The future outlook for interest rates is not solely dependent on the immediate 2026 forecast. It’s a dynamic process, subject to ongoing assessment of economic data and global events. While a 0.75% hike is a significant projection, subsequent decisions will depend on how the economy responds to this adjustment and whether inflationary pressures subside.
Analyzing the historical context reveals that the Fed’s actions are part of a continuous effort to achieve its dual mandate: maximum employment and price stability. The 2026 forecast is a snapshot in this ongoing journey, and staying informed about these broader economic trends is essential for financial planning.
| Key Impact Area | Brief Description of Effect |
|---|---|
| Mortgage Rates | New fixed rates will be higher; ARM payments will likely increase. |
| Savings Accounts | Expect higher yields on savings, CDs, and money market accounts. |
| Consumer Debt | Credit card, auto loan, and other variable debt costs will rise. |
| Economic Growth | Potential cooling of inflation but also a slowdown in business investment. |
Frequently Asked Questions About 2026 Interest Rate Hikes
A 0.75% Fed hike will not directly change your existing fixed-rate mortgage payments. Your interest rate is locked in for the life of the loan. However, it will affect new mortgage rates if you consider refinancing or buying another home.
Savings account rates typically increase relatively quickly, often within a few weeks or months, after a Fed hike. However, the exact timing and magnitude of the increase can vary between different banks and financial institutions.
It’s generally advisable to prioritize paying off variable-rate debt, such as credit card balances or certain personal loans, before anticipated interest rate hikes. This proactive approach can help you avoid higher interest costs once rates officially increase.
While a 0.75% hike aims to curb inflation, it also carries the risk of slowing economic growth. Whether it leads to a recession depends on various other economic factors and the overall resilience of the economy at that time.
In a rising interest rate environment, consider investments that benefit from higher yields, like short-term bonds or high-yield savings. Consulting a financial advisor is crucial to tailor strategies to your individual risk tolerance and financial goals.
Conclusion
The anticipated interest rate forecast 2026, with its projected 0.75% Fed hike, underscores a critical period for financial planning in the United States. From the significant shifts in mortgage affordability to the potential for enhanced savings returns, every aspect of personal and national finance stands to be influenced. Proactive engagement with these forecasts, coupled with informed decision-making regarding debt management, savings strategies, and investment portfolios, will be paramount for individuals and businesses alike to navigate the evolving economic landscape successfully. Staying informed and adaptable will be key to thriving amidst these changes.