High-Yield Savings Accounts 2026: Earn Over 5.2% APY
Anúncios
Investing in 2026: A Deep Dive into High-Yield Savings Accounts Offering Over 5.2% APY
Welcome to 2026, a year presenting unique opportunities for savvy savers and investors. In an economic climate characterized by evolving interest rates and innovative financial products, the quest for maximizing returns on your hard-earned money remains paramount. For those seeking stability coupled with significant growth potential, High-Yield Savings Accounts 2026 are emerging as a standout option, particularly those offering an Annual Percentage Yield (APY) exceeding 5.2%. This comprehensive guide will navigate the intricacies of these accounts, providing you with the knowledge to make informed decisions and secure your financial future.
Anúncios
The financial landscape is ever-changing, and staying ahead means understanding where the best opportunities lie. Traditional savings accounts often offer meager returns, barely keeping pace with inflation. However, the advent and proliferation of high-yield savings accounts have revolutionized how individuals approach their emergency funds and short-term savings goals. With the potential to earn over 5.2% APY, these accounts are no longer just a safe haven for your cash; they are a powerful tool for wealth accumulation.
Our exploration will cover everything from the fundamental mechanics of high-yield savings accounts to the specific factors driving their attractiveness in 2026. We will delve into how to identify the best accounts, understand the underlying economic forces influencing APY rates, and strategically position your savings for optimal growth. Whether you are a seasoned investor or new to the world of personal finance, this article is designed to equip you with actionable insights to harness the power of High-Yield Savings Accounts 2026.
Anúncios
Understanding High-Yield Savings Accounts in 2026
Before diving into the specifics of accounts offering over 5.2% APY, it’s crucial to grasp what defines a high-yield savings account and why they are particularly relevant in 2026. A high-yield savings account is essentially a savings account that offers significantly higher interest rates than the national average for traditional savings accounts. These accounts are typically offered by online banks or credit unions, which often have lower overhead costs compared to traditional brick-and-mortar institutions, allowing them to pass on higher earnings to their customers.
The Mechanics of APY: More Than Just Interest
APY, or Annual Percentage Yield, is a crucial metric to understand. It reflects the real rate of return on an investment, taking into account the effect of compounding interest. While interest rates might be quoted as a simple percentage, APY provides a more accurate picture of how much your money will grow over a year. For High-Yield Savings Accounts 2026, a 5.2% APY means that if you deposit a certain amount, after one year, you will have earned 5.2% of that initial deposit, plus any additional deposits, with interest compounding regularly (daily, monthly, or quarterly).
Why 2026 is a Pivotal Year for High-Yield Savings
Several economic factors contribute to the prominence of high-yield savings accounts in 2026. Global economic shifts, central bank policies, and inflation trends all play a role in determining interest rates. In 2026, we are observing a confluence of these factors that has created an environment where competitive APYs are not just possible but increasingly common. This makes it an opportune time to reassess your savings strategy and consider moving funds into accounts that offer superior returns.
Technological advancements in the banking sector have also made these accounts more accessible and user-friendly. Digital-first banks can operate with greater efficiency, translating into better rates for consumers. Furthermore, increased competition among financial institutions vying for consumer deposits has driven up APY offerings, benefiting those who are diligent in their search for the best rates. The landscape for High-Yield Savings Accounts 2026 is dynamic, favoring those who are proactive.
Identifying High-Yield Savings Accounts Over 5.2% APY
Finding an account that consistently offers over 5.2% APY requires a strategic approach. It’s not enough to simply search for ‘high-yield savings’; you need to know what to look for, where to look, and what questions to ask. The market is saturated with options, and while many claim high returns, the devil is often in the details.
Key Factors to Consider Beyond APY
- FDIC or NCUA Insurance: This is non-negotiable. Ensure your chosen institution is insured by the Federal Deposit Insurance Corporation (FDIC) for banks or the National Credit Union Administration (NCUA) for credit unions. This protects your deposits up to $250,000 per depositor, per institution, in case of bank failure. Peace of mind is priceless when it comes to your savings.
- Minimum Balance Requirements: Some high-yield accounts require a minimum deposit to open or maintain the advertised APY. Be sure to check these requirements to ensure they align with your financial capacity.
- Fees: Scrutinize the fee schedule. While many online high-yield accounts boast no monthly maintenance fees, watch out for hidden charges such as excessive withdrawal fees, transfer fees, or inactivity fees that could erode your earnings.
- Accessibility and Transfer Options: Consider how easily you can access your funds. While high-yield accounts are generally for savings, you might need to transfer money to a checking account for everyday expenses. Look for seamless integration with other banking services and quick transfer times.
- Customer Service: Even with online banks, reliable customer service is vital. Check reviews and ratings to ensure the institution has a reputation for responsive and helpful support.
- Variable vs. Fixed Rates: Most high-yield savings accounts offer variable rates, meaning the APY can fluctuate with market conditions. While this can be advantageous during rising interest rate environments, it also means your rate could drop. Understand the bank’s history of adjusting rates.
Where to Find the Best Rates
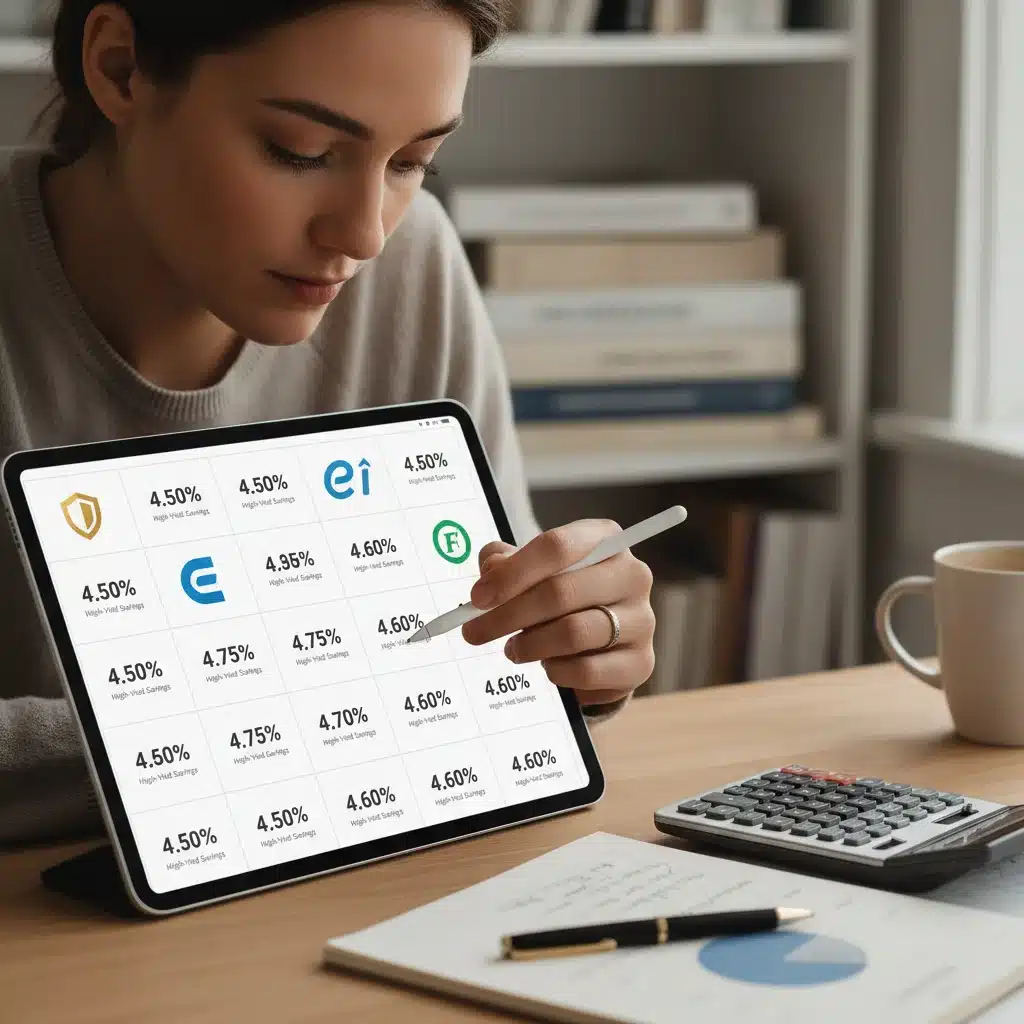
The best rates for High-Yield Savings Accounts 2026 are predominantly found at online-only banks and credit unions. These institutions often have lower operating costs, allowing them to offer more attractive APYs to attract and retain customers. Regularly check financial news websites, comparison tools, and aggregator sites that track the highest APY offerings. Be diligent, as rates can change frequently.
Maximizing Your Returns: Strategies for High-Yield Savings
Simply opening a high-yield savings account is the first step; maximizing its potential requires a strategic approach. Here are several strategies to ensure your High-Yield Savings Accounts 2026 work as hard as possible for you.
Automate Your Savings
One of the most effective ways to grow your savings is to make it automatic. Set up recurring transfers from your checking account to your high-yield savings account on payday. Even small, consistent contributions can add up significantly over time, especially with a 5.2% APY compounding your earnings.
Laddering Your Savings (for larger sums)
For individuals with larger sums of money, a savings ladder can be an effective strategy. While more commonly associated with Certificates of Deposit (CDs), a similar principle can be applied to high-yield savings accounts if you anticipate needing portions of your money at different times. By distributing your funds across accounts with slightly different access terms or even different institutions (to stay within FDIC limits), you can potentially optimize both liquidity and returns. However, for most high-yield savings, the primary benefit is the high liquidity combined with a strong APY, making complex laddering less necessary unless you’re managing exceptionally large sums.
Stay Informed and Be Ready to Switch
The market for High-Yield Savings Accounts 2026 is competitive. Banks constantly adjust their rates to attract new customers and retain existing ones. Regularly monitor the APY offered by your bank and compare it with competitors. If you find a significantly better rate elsewhere, don’t hesitate to switch. The process of transferring funds between FDIC-insured online banks is usually straightforward and can result in hundreds, if not thousands, of extra dollars in interest over time.
Understand the Tax Implications
The interest earned on your high-yield savings account is considered taxable income. Keep this in mind when planning your overall financial strategy. While the focus is on growth, being aware of the tax implications will help you avoid surprises come tax season. Consult with a financial advisor or tax professional for personalized advice.
The Benefits of High-Yield Savings Accounts in 2026
Beyond the attractive APY, High-Yield Savings Accounts 2026 offer a multitude of benefits that make them an indispensable component of a sound financial plan.
Superior Returns Compared to Traditional Accounts
This is the most obvious benefit. Earning over 5.2% APY on your savings significantly outperforms the paltry rates offered by most traditional savings accounts. This difference, especially when compounded over several years, can translate into substantial financial gains, helping your money grow faster than inflation.
Liquidity and Accessibility
Unlike investments tied up in the stock market or long-term CDs, high-yield savings accounts offer excellent liquidity. You can typically access your funds relatively quickly, often within one to three business days, making them ideal for emergency funds or short-term savings goals like a down payment on a house or a new car. This balance of high returns and accessibility is a key differentiator for High-Yield Savings Accounts 2026.
Security and Peace of Mind
As mentioned, most reputable high-yield savings accounts are FDIC or NCUA insured. This insurance provides a critical layer of security, protecting your deposits even if the financial institution fails. This peace of mind is something that volatile investments cannot offer, making high-yield savings an excellent choice for risk-averse savers.
Simplicity and Ease of Management
Managing a high-yield savings account is typically straightforward. Most online banks offer intuitive platforms and mobile apps that allow you to track your balance, view interest earned, and make transfers with ease. This simplicity makes them accessible to a wide range of individuals, regardless of their financial expertise.
Potential Downsides and How to Mitigate Them
While the advantages of High-Yield Savings Accounts 2026 are compelling, it’s important to be aware of potential downsides and how to mitigate them to ensure a smooth and profitable experience.
Variable Interest Rates
As discussed, most high-yield savings accounts have variable interest rates. This means the APY can change based on market conditions, central bank policies, and the bank’s own strategic decisions. While rates are currently favorable, there’s always a possibility they could decrease. To mitigate this, stay informed about economic forecasts and be prepared to switch banks if rates drop significantly.
Online-Only Experience
Many of the best high-yield accounts are offered by online-only banks, which means no physical branches. While this contributes to lower overhead and higher APYs, it can be a disadvantage for those who prefer in-person banking services. Ensure you are comfortable with digital banking and that the online bank offers robust customer support channels (phone, chat, email) to compensate for the lack of physical presence.
Withdrawal Limitations
While high-yield savings accounts offer liquidity, they are still subject to certain regulations, historically Regulation D, which limited certain types of withdrawals or transfers to six per statement cycle. Although Regulation D was suspended, banks may still impose their own limits. Always check the terms and conditions for any withdrawal limitations to avoid unexpected fees or restrictions on accessing your money.
Future Outlook for High-Yield Savings in 2026 and Beyond
What does the future hold for High-Yield Savings Accounts 2026? Predicting economic trends with absolute certainty is impossible, but we can analyze current trajectories and expert opinions to form a reasonable outlook.
Continued Competition and Innovation
The competitive landscape among online banks and fintech companies is likely to continue driving innovation and attractive APYs. As more consumers become aware of the benefits of high-yield savings, institutions will strive to offer competitive rates and features to capture market share.
Interest Rate Environment
Central bank policies and global economic stability will remain significant determinants of interest rates. While a 5.2% APY is strong in 2026, future rates will depend on inflation, economic growth, and monetary policy decisions. Staying abreast of these macroeconomic factors will be key to making timely adjustments to your savings strategy.
Integration with Broader Financial Planning
As financial technology evolves, we can expect greater integration of high-yield savings accounts with broader financial planning tools. This could include seamless connections with budgeting apps, investment platforms, and personalized financial advice, making it even easier to manage your money holistically.
Real-World Examples and Success Stories
To illustrate the power of High-Yield Savings Accounts 2026, let’s consider a hypothetical scenario. Sarah, a young professional, decided in early 2026 to move her $20,000 emergency fund from a traditional savings account earning 0.1% APY to a high-yield account offering 5.2% APY. After one year, her traditional account would have earned a mere $20. In contrast, her high-yield account would have earned approximately $1,040 in interest. This significant difference highlights the tangible benefits of choosing the right savings vehicle.
Another example is David, who is saving for a down payment on a house. He contributes $500 monthly to his high-yield savings account. With a 5.2% APY, his consistent contributions, combined with the power of compounding, accelerate his savings goal much faster than if he were using a low-interest account. These success stories are not outliers; they are common outcomes for those who leverage the potential of high-yield savings.
Choosing the Right High-Yield Savings Account for You
The ‘best’ High-Yield Savings Account 2026 isn’t a one-size-fits-all solution. It depends on your individual financial goals, habits, and preferences. Here’s a checklist to help you choose wisely:
- Define Your Goals: Are you saving for an emergency fund, a short-term purchase, or a long-term goal? Your timeline and liquidity needs will influence your choice.
- Assess Your Deposit Amount: If you have a large sum, you might be able to meet higher minimum balance requirements for potentially better rates. If you’re starting small, look for accounts with no minimums.
- Review the Fine Print: Always read the terms and conditions carefully. Pay attention to fees, withdrawal limits, and any introductory rates that might change after a period.
- Compare Multiple Options: Don’t settle for the first account you find. Use comparison websites and financial aggregators to survey the market and identify the top contenders.
- Consider Customer Reviews: While APY is important, so is the overall banking experience. Check online reviews and ratings to gauge customer satisfaction with service, online platforms, and issue resolution.
Making an informed decision today can significantly impact your financial well-being tomorrow. The market for High-Yield Savings Accounts 2026 is robust, offering unprecedented opportunities for growth. By taking the time to research and select the right account, you can ensure your money is working as hard as possible for you.
Conclusion: Secure Your Financial Future with High-Yield Savings
In conclusion, 2026 stands out as an exceptional year for leveraging High-Yield Savings Accounts 2026. With APYs exceeding 5.2%, these accounts offer a compelling combination of high returns, liquidity, and security, making them an ideal choice for emergency funds, short-term savings, and even as a stable component of a diversified investment portfolio.
The key to success lies in understanding the market, diligently researching institutions, and strategically managing your funds. By prioritizing FDIC/NCUA insurance, scrutinizing fees, and staying agile in a dynamic interest rate environment, you can harness the full potential of these powerful financial tools. Don’s let your money sit idle in low-interest accounts. Empower your savings, achieve your financial goals faster, and secure a more prosperous future by embracing the opportunities presented by high-yield savings accounts in 2026.
Start your journey today by exploring the top-tier High-Yield Savings Accounts 2026 and take control of your financial destiny. Your future self will thank you.
Author